Author: ketandev

  • **Finance vs. Accounting?: What the Evidence Actually Shows**

    **Finance vs. Accounting?: What the Evidence Actually Shows**

    Header image source: Accounting vs Finance Degree: What’s Right For Me? | Franklin.edu via Franklin University via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Accounting records past transactions using strict GAAP rules
    • Finance uses economic theories for forward-looking decisions
    • Finance careers often pay more but demand more strategic judgment

    Finance and accounting are not the same thing. Full stop. Accounting is the meticulous, rules-bound process of recording what has already happened—transactions, expenses, revenues—so financial statements can be produced with precision. Finance is the analytical, forward-looking discipline that uses those statements (and other data) to predict, model, and optimize what should happen next: investments, capital allocation, risk management. This isn’t some subtle nuance. It’s a fundamental divide in temporal orientation, methodology, and career trajectory.

    The data doesn’t lie. Accounting operates within rigid frameworks like GAAP and IFRS, dictating everything from revenue recognition to asset depreciation. Finance has no universal rulebook. Instead, it leans on economic theories—Capital Asset Pricing Model, efficient market hypothesis—and statistical tools like discounted cash flow models and Monte Carlo simulations. Harvard Business School Online puts it bluntly: finance is about strategic decision-making, while accounting is about compliance and reporting. That distinction shapes everything from the software professionals use to the salaries they command.


    Past vs. Future: The Core Divide

    Accounting is the historian of business. Every source confirms this. Becker CPA Review describes it as looking at past financial transactions and records. Southern New Hampshire University is even more direct: accounting generally works with existing records and documents. This isn’t a flaw—it’s the entire point. Accounting’s role is to produce accurate, auditable financial statements—balance sheets, income statements, cash flow statements—that stakeholders can trust. Without this retrospective rigor, finance would have no reliable data to work with.

    Finance is the strategist. Northwest Missouri State University notes it emphasizes analysis and forward-looking decisions. Frontline Source Group frames it as a contrast: accounting focuses on what has already happened, while finance focuses on what should happen next. This isn’t just semantics. A financial analyst building a discounted cash flow model to value a potential acquisition isn’t verifying past transactions—they’re making assumptions about future cash flows, discount rates, and terminal values. An accountant preparing a tax return is ensuring last year’s revenue and expenses were recorded correctly under IRS rules.

    The overlap exists. Both fields rely on financial statements. But accounting produces them. Finance interprets them to make decisions. This explains why finance professionals often work in dynamic, high-stakes environments—investment banking, private equity, corporate strategy—while accountants dominate roles requiring precision and compliance: auditing, tax advisory, regulatory reporting.


    Rules vs. Judgment: The Methodology Chasm

    Accounting is a discipline of constraints. GAAP and IFRS aren’t suggestions—they’re mandates. Harvard Business School Online highlights this: accounting operates within strict guidelines to ensure consistency. Under GAAP, revenue is recognized when earned, not when cash is received. This rule applies universally, whether you’re a multinational corporation or a local bakery. The rigidity is intentional. It ensures financial statements are comparable across companies and industries, which is critical for investors, regulators, and auditors.

    Finance has no such universal standards. It’s a field of trade-offs. Accounting.com puts it well: finance professionals weigh risk versus return, debt versus equity, and short-term versus long-term goals. These decisions aren’t governed by rules—they’re guided by economic theories, market conditions, and professional judgment. A CFO deciding whether to issue debt or equity to fund an expansion isn’t following a playbook. They’re analyzing interest rates, credit markets, tax implications, and the company’s risk tolerance. A portfolio manager choosing between stocks and bonds isn’t verifying past transactions—they’re forecasting future returns based on macroeconomic trends, sector performance, and company fundamentals.

    This methodological divide has real consequences. Auditors verify compliance with GAAP. CFOs decide whether to acquire a competitor based on projected synergies. One is about accuracy. The other is about strategy. One is backward-looking. The other is forward-looking. One is rules-bound. The other is judgment-driven.


    Tools of the Trade: Precision vs. Prediction

    The tools professionals use reflect these differences sharply.

    Accounting’s toolkit is built for precision and compliance. ERP systems like QuickBooks, SAP, and Oracle dominate the field. These platforms handle invoicing, payroll, financial reporting—ensuring transactions are recorded accurately and reconciled properly. Tax software like TurboTax and CCH ProSystem fx automates compliance with ever-changing tax laws. The focus here is on accuracy, audit trails, and regulatory adherence. Becker notes that accounting professionals spend significant time reconciling accounts and ensuring financial statements are error-free.

    Finance’s toolkit is built for analysis and prediction. Bloomberg Terminals provide real-time market data, news, and analytics for traders and portfolio managers. Python and R are used to build predictive models, backtest trading strategies, and analyze large datasets. Platforms like Tableau and Power BI visualize financial trends and performance metrics. Finance professionals rely on sophisticated models—discounted cash flow for valuation, Black-Scholes for options pricing, Value at Risk for risk assessment. Northwest Missouri State University notes that finance students learn to use these tools to evaluate investment opportunities, manage risk, and optimize financial performance.

    AI is reshaping both fields—but differently. In accounting, AI automates repetitive tasks: data entry, invoice processing, fraud detection. Machine learning algorithms flag anomalies in expense reports or predict tax liabilities based on historical data. Human oversight remains critical for tasks requiring judgment—interpreting complex tax laws, signing off on audits. In finance, AI powers predictive analytics: credit scoring, algorithmic trading, portfolio optimization. Machine learning models analyze market trends, predict stock prices, identify investment opportunities. But finance professionals must still interpret these outputs, assess their reliability, and make final decisions.


    Career Paths: Salaries, Specializations, and Trade-Offs

    The career trajectories in finance and accounting diverge sharply—reflecting their distinct focuses.

    Accounting’s specialization is both its strength and its limitation. Roles like Certified Public Accountant, auditor, and tax advisor demand deep expertise in regulations and compliance. Accounting jobs typically require a bachelor’s degree, often with additional certifications—CPA, Certified Management Accountant. The Big 4—Deloitte, PwC, EY, KPMG—dominate the industry, offering clear career paths from staff accountant to manager to partner. But the work can be repetitive, with busy seasons—tax season, quarterly reporting—demanding long hours. Salaries reflect this specialization. A staff accountant earns a competitive salary. A CPA in a Big 4 firm can earn substantial compensation with experience.

    Finance’s breadth offers more variety—but also more competition. Careers span investment banking, corporate finance, asset management, financial planning. Northwest Missouri State University highlights that finance graduates study corporate finance, investments, financial markets, and risk management. Roles like investment banker, financial analyst, portfolio manager demand strong analytical skills and the ability to thrive under pressure. Salaries in finance are typically higher. An investment banking analyst can earn substantial compensation in their first year. Hedge fund managers or private equity associates can earn high compensation. But the hours are brutal—long work weeks are common in investment banking—and the career ladder is steep.

    The hybrid path is increasingly common. Many professionals start in accounting to build technical skills and earn certifications—CPA—before transitioning to finance. The Chartered Financial Analyst designation is a popular bridge, offering deep training in investment analysis, portfolio management, and financial modeling. This path combines the rigor of accounting with the strategic focus of finance, making it ideal for roles like financial planning and analysis, corporate development, or asset management.


    Education: What You Learn—and Why It Matters

    The curricula for finance and accounting majors reflect their distinct priorities—no surprises there.

    Accounting programs drill into technical skills and regulatory knowledge. Students master GAAP and IFRS, learning how to record transactions, prepare financial statements, and comply with tax laws. Courses cover auditing, tax accounting, managerial accounting, forensic accounting. Accounting students spend significant time learning to use tools for financial modeling and data management. The goal? Graduates who can ensure accuracy and compliance in financial reporting.

    Finance programs prioritize analytical and strategic thinking. Students study corporate finance—capital budgeting, cost of capital—investments—portfolio management, asset pricing—financial markets—equities, fixed income, derivatives—and risk management. SNHU notes that finance students learn to analyze financial data, assess risk, and make strategic financial decisions. Courses often include statistical analysis, econometrics, and financial modeling using Python and R. The focus is on developing skills to forecast performance, evaluate investment opportunities, and optimize capital structure.

    Overlap exists, but it’s limited. Both majors require foundational courses in economics, statistics, and business law. Finance leans into quantitative methods and economic theory. Accounting emphasizes compliance and technical precision. A finance major might take behavioral finance to understand market irrationality. An accounting major might study forensic accounting to detect fraud.


    Industry Applications: Where Each Discipline Dominates

    The industries where finance and accounting thrive reflect their core strengths—compliance versus strategy.

    Accounting is critical in regulated industries where transparency is non-negotiable. Healthcare, government, nonprofits rely heavily on accountants to ensure adherence to regulations. Auditors verify financial statements. Tax professionals navigate complex tax laws. Frontline Source Group highlights that accounting is essential for ensuring that financial records are accurate and compliant with laws and regulations. Precision, accountability, risk mitigation—these are the priorities.

    Finance drives strategy in dynamic sectors where growth and innovation are paramount. Technology, private equity, venture capital are dominated by finance professionals evaluating investment opportunities, optimizing capital structure, managing risk. Harvard Business School Online notes that finance is more strategic and forward-looking, making it indispensable in industries where rapid decision-making is critical. CFOs in tech companies balance short-term cash flow needs with long-term growth investments. Portfolio managers in asset management allocate capital across asset classes to maximize returns.

    Public vs. private sectors further highlight these differences. In the public sector, accounting is vital for budgeting, auditing, regulatory compliance. Government agencies and nonprofits rely on accountants to manage funds transparently and ensure accountability. In the private sector, finance dominates capital markets—raising capital, managing investments, optimizing financial performance. But both fields operate across sectors. A CFO in a Fortune 500 company needs accounting expertise for accurate financial reporting and finance skills to guide strategic decisions.


    The AI Factor: Automation’s Double-Edged Sword

    AI is disrupting both fields—but in different ways, at different speeds.

    Accounting’s automation focuses on efficiency and accuracy. AI-powered tools handle repetitive tasks: data entry, invoice processing, bank reconciliations. Machine learning algorithms detect anomalies in financial data, flagging potential errors or fraud. AI can scan expense reports for duplicates or unusual spending patterns, reducing manual review. But human oversight remains critical for tasks requiring judgment—interpreting complex tax laws, signing off on audits. Becker notes that while AI can automate routine tasks, human accountants are still needed to provide strategic advice and ensure compliance.

    Finance’s AI adoption is more transformative. Machine learning models analyze vast datasets to predict market trends, optimize portfolios, assess credit risk. Algorithmic trading systems execute trades at speeds and volumes impossible for humans. Robo-advisors provide automated investment advice to retail investors. But finance professionals must still interpret these outputs, assess their reliability, and make final decisions. Northwest Missouri State University highlights that AI enhances predictive modeling but does not replace the need for human judgment in financial decision-making.

    Job security in both fields is evolving. Accounting roles focused on data entry and reconciliation are at risk of automation. Those requiring strategic advice and compliance expertise remain secure. Finance roles involving predictive modeling and risk assessment are becoming more data-driven. But the need for human judgment persists. The key for professionals in both fields? Develop skills that complement AI—critical thinking, strategic analysis, ethical judgment.


    Which Should You Choose? The Decision Isn’t Binary

    The choice between finance and accounting isn’t about which is "better. " It’s about which aligns with your strengths, interests, and ambitions. The evidence is clear: accounting is the foundation. Finance is the strategy. One records the past. The other shapes the future.

    Pick accounting if:

    • You thrive in structured, detail-oriented environments.
    • You enjoy working with rules and regulations.
    • You want a clear career path with specialized roles—CPA, auditor, tax advisor.
    • You’re comfortable with repetitive tasks and busy seasons—tax season, quarterly reporting.
    • You’re interested in industries where compliance is critical—healthcare, government, nonprofits.

    Pick finance if:

    • You prefer analytical, strategic thinking.
    • You enjoy modeling, forecasting, and risk assessment.
    • You want higher earning potential and dynamic career opportunities—investment banking, corporate finance, asset management.
    • You’re comfortable with ambiguity and high-pressure environments.
    • You’re interested in industries where growth and innovation are priorities—tech, private equity, venture capital.

    The hybrid path is worth considering. Start in accounting to build technical skills and earn certifications—CPA—before transitioning to finance. The CFA designation is a popular bridge, offering deep training in investment analysis and portfolio management. This path combines the rigor of accounting with the strategic focus of finance, making it ideal for roles like financial planning and analysis, corporate development, or asset management.

    The open question isn’t which field to choose. It’s how you’ll adapt as AI reshapes both. Will the next generation of accountants become more strategic advisors, leveraging AI for compliance but focusing on high-value insights? Will finance professionals rely even more on predictive models, or will human judgment regain primacy as markets grow more volatile? The divide between finance and accounting isn’t disappearing. But the lines between them might blur faster than anyone expects.


  • **What Is Finance in an MBA? A Data-Backed Breakdown of Its Role, Value, and Distinctions**

    **What Is Finance in an MBA? A Data-Backed Breakdown of Its Role, Value, and Distinctions**

    Header image: MBA Display by keisasaki, CC BY 2.0, via flickr via Openverse — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • An MBA in Finance combines broad business leadership with specialized financial expertise
    • The degree targets mid-to-upper management and executive roles like CFO
    • Finance is among the most popular and highest-paying MBA concentrations

    An MBA in Finance isn’t about becoming a spreadsheet jockey. It’s about learning to weaponize financial expertise as a leadership lever—shaping strategy, driving decisions, and turning numbers into business impact. The distinction from a Master of Finance isn’t subtle: while the latter drills deep into quantitative analysis and financial theory, an MBA in Finance delivers both broad management training and targeted financial acumen. That dual engine is what makes the degree uniquely valuable for professionals who need to bridge the C-suite and the balance sheet.

    Here’s the core truth: An MBA in Finance is a graduate business degree with a financial specialization, designed for those who must make—or oversee—high-stakes financial decisions in a leadership context. It’s not a technical finance degree. It’s a management degree with a financial lens, covering asset management, investment strategy, and global markets, always within a framework of business leadership. If your sights are set on roles like CFO, VP of Finance, or investment banking director, this is the degree built for that trajectory.


    The Dual Engine: How an MBA in Finance Actually Works

    The MBA in Finance isn’t just finance courses stapled onto a generic MBA. It’s a deliberate fusion of broad business training and specialized financial expertise—and that distinction is everything. Here’s how it actually breaks down:

    The Breadth: Core Business Leadership

    Every MBA program, regardless of concentration, demands coursework in:

    • Leadership and organizational behavior: managing teams, navigating office politics, driving cultural change.
    • Business strategy: competitive analysis, market positioning, long-term planning.
    • Marketing management: customer behavior, branding, go-to-market strategies.
    • Operations and supply chain: optimizing processes, logistics, resource allocation.
    • Data-driven decision-making: using analytics to inform strategy, not just instinct.

    This is the business foundation that separates an MBA from a technical degree. It’s why an MBA in Finance graduate can step into leadership in healthcare, tech, manufacturing—not just finance. The degree doesn’t just teach you how to read a balance sheet. It teaches you how to use that balance sheet to steer a company.

    The Depth: Financial Specialization

    The finance concentration layers on targeted expertise in:

    • Financial decision-making processes: how companies allocate capital, evaluate investments, manage risk.
    • Global financial markets: how macroeconomic trends, interest rates, and geopolitical events shape financial strategies.
    • Investment strategy and portfolio management: building and managing assets for individuals, corporations, or institutional investors.
    • Corporate finance and valuation: assessing company worth, structuring deals, optimizing capital structure.

    The finance curriculum is designed to provide "an understanding of the finance decision-making process and insights into how financial markets function. " This isn’t about memorizing formulas. It’s about applying financial tools to real-world business challenges.

    Why This Dual Structure Actually Matters

    The magic of the MBA in Finance lies in how it integrates these two halves. A Master of Finance might teach you how to build a discounted cash flow model. An MBA in Finance teaches you how to use that model to convince a CEO to pivot the company’s strategy. It’s the difference between being a financial analyst and being the person who leads the finance team.

    Consider the CFO role. They don’t just crunch numbers. They shape the financial narrative of the company, advising the CEO on everything from capital allocation to mergers and acquisitions. That’s the kind of role an MBA in Finance is built for. The degree prepares graduates to "rise to top-level roles after years of experience in finance management," not just entry-level positions.

    The Data Point: Finance as a High-Value Concentration

    Finance isn’t just popular. It’s one of the most lucrative MBA concentrations. Finance ranks among the top 10 highest-paying MBA concentrations. That’s not surprising when you look at the career trajectories it enables. MBAs were almost five times more likely to choose finance as a concentration compared to other specializations. The numbers don’t lie: demand is strong, and ROI is real.


    The Leadership Dividend: Why the MBA in Finance Targets Executive Roles

    The MBA in Finance isn’t designed for entry-level roles. It’s explicitly built for mid-to-upper management and executive positions—where financial expertise intersects with leadership. Here’s the evidence:

    Career Trajectory: From Manager to Executive

    Graduates with an MBA in Finance typically progress from early career roles to mid-career positions to executive roles.

    The degree is recommended for those aiming for executive leadership, not just financial analysis. "An MBA in finance is a graduate-level degree that focuses on business and finance courses," and it’s "geared toward individuals wanting to take management courses in finance and expand their finance analytical and strategic skills. "

    Versatility Across Industries

    Unlike a Master of Finance—which is often finance-industry-specific—an MBA in Finance is valued in any sector where financial strategy intersects with leadership. Here’s where you’ll find finance MBAs:

    • Financial services: banks, asset management firms, insurance companies, private equity.
    • Consulting: McKinsey, BCG, Deloitte—where financial acumen is critical for advising clients.
    • Tech: FAANG companies, where finance teams manage everything from R&D budgets to M&A.
    • Healthcare: hospital systems and pharma companies, where financial strategy drives patient care and drug development.
    • Manufacturing: supply chain finance, capital investments, mergers.

    This versatility is a key advantage. If you’re in a finance role at a tech company, you’re not just managing budgets. You’re helping shape the company’s growth strategy, evaluate acquisitions, allocate resources across teams. That’s the cross-functional leadership the degree prepares you for.

    Concentration Popularity: A Signal of Demand

    The fact that finance is one of the most popular MBA concentrations isn’t just anecdotal. It’s backed by data. Research found that MBAs were almost five times more likely to choose finance compared to other specializations. That suggests strong perceived ROI, especially for roles like CFO or VP of Finance, where the combination of leadership and financial expertise commands a premium.


    The Curriculum: What You Actually Study (And Why It’s Not Just “Finance”)

    The curriculum of an MBA in Finance is where the dual engine of the degree becomes concrete. It’s not just a list of finance courses. It’s a deliberate blend of leadership training and financial expertise. Here’s what you’ll actually study:

    Core MBA Courses: The Business Foundation

    Every MBA student, regardless of concentration, takes a set of core courses covering business leadership fundamentals:

    • Leadership and organizational behavior: managing teams, navigating power dynamics, driving cultural change. This isn’t just theory. It’s about leading people, whether in finance or any other function.
    • Business strategy and competitive analysis: how companies position themselves in markets, respond to competitors, sustain long-term advantage. This is where finance meets big-picture thinking.
    • Marketing management: customer behavior, branding, go-to-market strategies. Finance leaders need to know how marketing investments drive revenue—and how to allocate budgets accordingly.
    • Operations and supply chain management: optimizing processes, logistics, resource allocation. Even in finance, you’ll need to understand how operational decisions impact the bottom line.
    • Data-driven decision-making: using analytics to inform strategy. This isn’t just about Excel. It’s about turning data into actionable insights.

    These courses aren’t finance-specific, but they’re essential for anyone aiming for a leadership role. A CFO doesn’t just need to understand financial statements. They need to communicate financial insights to non-finance executives, align financial strategy with business goals, lead teams through change.

    Finance Concentration Courses: The Specialized Deep Dive

    The finance concentration adds targeted coursework that varies by program but typically includes:

    • Financial reporting and analysis: reading and interpreting financial statements, assessing company performance, identifying red flags.
    • Investment strategy and portfolio management: building and managing assets for individuals, corporations, or institutional investors. This isn’t just about stocks and bonds. It’s about aligning investments with business goals.
    • Corporate finance and valuation: assessing company worth, structuring deals, optimizing capital structure. This is where finance meets strategic decision-making.
    • Global financial markets: how macroeconomic trends, interest rates, and geopolitical events shape financial strategies. A finance leader needs to understand how global forces impact their company’s bottom line.
    • Financial decision-making processes: how companies allocate capital, evaluate investments, manage risk. This is the applied side of finance—where theory meets real-world strategy.

    The finance curriculum is designed to provide "an understanding of the finance decision-making process and insights into how financial markets function. " That’s a far cry from the technical depth of a Master of Finance. The MBA in Finance is about applying financial tools to business challenges, not just mastering them.

    The Key Differentiator: Management Lens

    The finance coursework in an MBA program is taught through a management lens. For example:

    • A course on investment strategy won’t just teach you how to build a portfolio. It’ll teach you how to align investments with business goals.
    • A course on corporate finance won’t just teach you how to value a company. It’ll teach you how to advise a CEO on capital allocation.
    • A course on global financial markets won’t just teach you about interest rates. It’ll teach you how to navigate geopolitical risks in your company’s strategy.

    This is the executive readiness that sets the MBA in Finance apart. The degree prepares graduates to translate financial data into business strategy—a skill that’s critical for leadership roles.

    The Criticism: Where the MBA in Finance Falls Short

    Some programs (like Franklin University’s) acknowledge that a Master of Finance goes deeper into technical topics like:

    • Quantitative finance: advanced mathematical models for pricing derivatives, managing risk, algorithmic trading.
    • Advanced derivatives: complex financial instruments like options, futures, swaps.
    • Financial engineering: the intersection of finance, math, and computer science.

    The MBA in Finance prioritizes applied financial leadership over technical depth. For some roles (e.g., quant analyst, risk modeler), a Master of Finance might be the better choice. But for leadership roles, the MBA’s broader perspective is an advantage.


    The Time and Cost Equation: What It Really Takes

    Earning an MBA in Finance isn’t quick or cheap. It’s a significant investment—in time, money, and opportunity cost. Here’s what you need to know:

    Duration: 1–2 Years (Or More)

    • Traditional MBA in Finance: typically 2 years for full-time students. This is the standard at top programs.

    Accelerated options: some programs offer 12–18 month tracks for working professionals. These are designed for students who can’t afford to step away from their careers for two years.

    • Part-time/online options: many schools offer part-time or online MBAs in Finance, which can take 2–3 years to complete while working. These are ideal for professionals who need to earn while they learn.

    The time commitment is a major factor. If you’re already in a high-paying finance role, stepping away for two years might not make sense—unless the long-term ROI justifies it.

    Cost: $20K–$150K+ (And Beyond)

    The cost varies widely depending on the school:

    • Top-tier programs: $100K–$150K+ (e.g., NYU Stern, Wharton, Harvard). These programs offer prestige, networks, and high ROI—but at a steep price.
    • Mid-tier programs: $20K–$50K (e.g., Franklin University, University of Bridgeport). These are more affordable but may lack the brand recognition of top schools.
    • Online/part-time options: often cheaper than full-time programs, but may offer less networking and career support.

    The ROI depends on your career goals. If you’re targeting executive roles (e.g., CFO, VP of Finance), the degree can pay for itself quickly. Finance is one of the top 10 highest-paying MBA concentrations, reflecting strong demand for professionals who can bridge finance and leadership.

    Opportunity Cost: The Hidden Price

    The biggest cost isn’t tuition. It’s the opportunity cost of stepping away from your career for 1–2 years. If you’re already earning a high salary in finance (e.g., $100K+ as a financial analyst or investment banker), the lost income can be substantial.

    For career switchers (e.g., moving from engineering to finance), the opportunity cost is lower, and the MBA can accelerate the transition. But for those already in finance, the decision to pursue an MBA is not just about the degree. It’s about the career trajectory.

    ROI Considerations: When the Degree Pays Off

    The MBA in Finance is most valuable for career switchers, promotion accelerators, industry pivots, and entrepreneurs.

    For those already in finance, the degree’s value depends on where you’re headed. If you’re aiming for technical roles (e.g., quant analyst, risk modeler), a Master of Finance might be a better fit. But if you’re targeting leadership roles, the MBA’s broader perspective is a major advantage.


    MBA in Finance vs. Master of Finance: The Critical Trade-Offs

    The choice between an MBA in Finance and a Master of Finance is one of the most important decisions for finance professionals. These degrees serve different purposes, and the right choice depends on your career goals. Here’s the breakdown:

    | Factor | MBA in Finance | Master of Finance | |————————–|——————————————–|——————————————–| | Primary focus | Leadership + financial strategy | Technical finance expertise | | Curriculum breadth | Broad business training | Deep dive into finance theory/methods | | Career trajectory | Mid-to-executive leadership (CFO, VP) | Technical roles (quant analyst, portfolio manager) | | Industry versatility | High (valued in any sector) | Lower (mostly finance industry) | | Time to complete | 1–2 years | 1–1.5 years | | Prerequisites | Work experience preferred | Often requires finance/math background |

    When to Choose an MBA in Finance

    The MBA in Finance is the right choice if:

    • You want leadership roles, not just technical ones. The degree is designed for executive trajectories, like CFO or VP of Finance.
    • You’re switching industries (e.g., from tech to finance). The MBA’s broad business training makes it easier to pivot.
    • You need strategic, not just analytical, skills. The degree teaches you how to translate financial data into business strategy.
    • You value versatility. An MBA in Finance is valued in any sector, not just finance.

    "An MBA in finance is likely a better choice if you hope to attain an executive leadership position eventually. " That’s the core value proposition.

    When to Choose a Master of Finance

    The Master of Finance is the right choice if:

    • You’re early in your finance career and need technical depth. The degree is ideal for roles like quant analyst, risk modeler, or portfolio manager.
    • You’re targeting quantitative roles (e.g., algorithmic trading, financial engineering). The Master of Finance goes deeper into math, statistics, and programming.
    • You lack a finance background but want to enter the field quickly. The degree is more accessible for career switchers without prior finance experience.
    • You’re not interested in leadership. If you love the technical side of finance and don’t want to manage people, the Master of Finance is a better fit.

    While an MBA in Finance covers financial theory, mathematics, and quantitative finance, the Master of Finance delves deeper into those topics. That’s the key trade-off: depth vs. breadth.

    The Hybrid Option: Dual Degrees

    Some schools offer dual-degree programs combining an MBA with a Master of Finance. These are intensive but can be ideal for professionals who want both leadership training and technical expertise. Examples:

    • Wharton’s MBA/Master of Finance: combines Wharton’s MBA with a deep dive into quantitative finance.

    Examples include MBA/Master of Finance dual-degree programs at various schools.

    These programs aren’t for the faint of heart, but they can be a powerful option for those who want the best of both worlds.


    The Job Market: Where an MBA in Finance Actually Takes You

    An MBA in Finance isn’t just a degree. It’s a career accelerator. The job market for finance MBAs is strong, but it’s not uniform. The roles you’ll land depend on your experience, network, and the reputation of your program. Here’s where the degree can take you:

    Top Roles for MBA in Finance Graduates

    The MBA in Finance is designed for executive and leadership roles, not entry-level positions. Here are the top roles graduates pursue:

    1. Chief Financial Officer (CFO): the ultimate finance leadership role. CFOs oversee all financial operations, report to the CEO, shape the company’s financial strategy. This is the pinnacle of the finance career ladder.
    2. VP of Finance: leads financial planning, analysis, and strategy for a business unit or the entire company. This role is a stepping stone to CFO.
    3. Investment Banker (Director/MD level): advises on mergers, acquisitions, and capital raising. At the director or managing director level, this role is about client relationships and deal-making, not just financial modeling.
    4. Corporate Treasurer: manages liquidity, investments, and risk for a corporation. This role is critical for capital-intensive industries (e.g., manufacturing, energy).
    5. Private Equity/Venture Capital Associate: evaluates investment opportunities, conducts due diligence, manages portfolio companies. This role is highly competitive and often requires prior finance experience.
    6. Financial Consultant: advises companies on financial strategy, restructuring, performance improvement. Firms like McKinsey, BCG, and Deloitte actively recruit finance MBAs for these roles.

    Industries Hiring Finance MBAs

    Finance MBAs aren’t limited to Wall Street. The degree’s versatility means it’s valued across industries. Here’s where you’ll find finance MBAs:

    • Financial services: banks (JPMorgan, Goldman Sachs), asset management firms (BlackRock, Fidelity), insurance companies (AIG, Prudential), private equity (KKR, Carlyle).
    • Consulting: McKinsey, BCG, Deloitte—where financial acumen is critical for advising clients.
    • Tech: FAANG companies (Google, Amazon, Apple), where finance teams manage everything from R&D budgets to M&A.
    • Healthcare: hospital systems (HCA, Ascension), pharma companies (Pfizer, Moderna), where financial strategy drives patient care and drug development.
    • Manufacturing: automotive (Ford, Tesla), aerospace (Boeing, Lockheed Martin), where finance teams manage supply chain costs, capital investments, mergers.
    • Energy: oil and gas (Exxon, Shell), renewables (NextEra Energy), where financial strategy shapes long-term investments.

    Salary Data: What Finance MBAs Earn

    Finance is one of the highest-paying MBA concentrations, and the salary data reflects that. Here’s what you can expect:

    • Entry-level (0–2 years of experience): $90K–$120K (e.g., financial analyst, associate in investment banking).
    • Mid-career (3–7 years of experience): $120K–$200K (e.g., finance manager, director).
    • Executive (10+ years of experience): $200K–$500K+ (e.g., CFO, VP of Finance, managing director in private equity).

    At top schools, median base salaries for finance MBAs are substantial. With bonuses and equity, total compensation can be substantial for mid-career professionals.

    For CFOs, the numbers are even higher. CFO compensation at top companies can be substantial.

    The Hidden Job Market: Network and Reputation

    The visible job market (e.g., LinkedIn postings, campus recruiting) is just the tip of the iceberg. Many finance leadership roles are filled through networks, and an MBA in Finance can open doors that would otherwise be closed.

    Here’s how:

    • Alumni networks: top MBA programs have powerful alumni networks in finance leadership (e.g., Goldman Sachs, BlackRock, Fortune 500 CFOs). These networks can fast-track your career.
    • Case competitions and consulting projects: many MBA programs offer real-world projects with companies, giving you exposure to finance leaders.
    • On-campus recruiting: investment banks, private equity firms, and consulting companies actively recruit finance MBAs from top programs.

    The reputation of your program matters. A finance MBA from a top program will open more doors than one from a lesser-known school. That’s not to say you can’t succeed with a degree from a mid-tier program—but you’ll need to work harder to build your network and reputation.


    The Hidden Value: What the Degree Actually Signals

    An MBA in Finance isn’t just a credential. It’s a signal. To employers, it communicates specific capabilities that go beyond technical finance skills. Here’s what the degree really says about you:

    Leadership Credibility

    The MBA in Finance signals that you can:

    • Translate financial data into business strategy. You don’t just understand the numbers. You know how to use them to drive decisions.
    • Lead teams through high-stakes financial decisions. Whether it’s a merger, a capital restructuring, or a crisis, you’ve been trained to navigate complexity.
    • Communicate financial insights to non-finance executives. A CFO doesn’t just talk to the finance team. They advise the CEO and board. The MBA in Finance prepares you for that.

    This is the executive readiness that sets the degree apart. The MBA in Finance develops "well-rounded leaders" while providing "financial expertise with a management context. "

    Network Effects

    The network you gain from an MBA in Finance is invaluable. Here’s how it pays off:

    • Alumni connections: top programs have alumni networks in finance leadership (e.g., Goldman Sachs, BlackRock, Fortune 500 CFOs). These connections can open doors to jobs, mentorship, deals.
    • Case competitions and consulting projects: many MBA programs offer real-world projects with companies, giving you exposure to finance leaders. These projects can lead to job offers.
    • Peer networks: your classmates will go on to lead companies, start businesses, shape industries. These relationships can pay dividends throughout your career.

    The hidden job market—roles filled through networks, not public postings—is huge in finance. An MBA in Finance gives you access to that market.

    Adaptability: The Versatility Advantage

    The MBA in Finance isn’t industry-specific. That means it’s valuable for professionals who may pivot sectors over their careers. For example: a finance MBA might move from investment banking to tech finance, from manufacturing to healthcare, or from consulting to private equity.

    This adaptability is a key advantage. In a world where industries are constantly disrupted, the ability to pivot is invaluable.

    Opinion: The MBA in Finance Is About Executive Readiness

    Here’s the real value: it’s not about technical mastery. It’s about executive readiness. Employers hire these graduates not to build models, but to shape financial strategy at the highest levels.

    That’s why the degree is so valuable for leadership roles. A CFO doesn’t just need to understand financial statements. They need to communicate financial insights to the CEO, align financial strategy with business goals, lead teams through change. The MBA in Finance prepares you for that.


    The Future: How AI and Disruption Are Reshaping Finance in MBAs

    Here’s how the degree is evolving—and what it means for your career:

    AI’s Impact on Finance Roles

    AI is automating routine tasks in finance. That’s reducing demand for entry-level finance jobs—but increasing demand for strategic finance leaders who can:

    • Interpret AI-generated financial insights. AI can crunch numbers, but humans are still needed to make sense of them.
    • Make judgment-based decisions. Capital allocation, risk management, and M&A aren’t easily automated. These require human judgment.
    • Lead digital transformation in finance functions. Companies need finance leaders who can integrate AI into financial processes and drive innovation.

    The MBA in Finance is well-positioned to meet this demand. The degree’s focus on leadership and strategy aligns with the new skills needed in finance.

    How MBA Programs Are Adapting

    Here’s how:

    • AI/ML coursework: many programs are adding AI and machine learning to their finance concentrations. For example, some programs offer FinTech electives covering blockchain, crypto, and AI in finance.
    • Data storytelling: finance leaders need to communicate financial insights to non-finance executives. MBA programs are emphasizing data storytelling—turning financial data into actionable business narratives.
    • Blockchain and crypto: these technologies are reshaping finance, and MBA programs are integrating them into corporate finance curricula.
    • Behavioral finance: AI can’t replace human judgment—but it can augment it. MBA programs are adding behavioral finance coursework to help students understand how psychology shapes financial decisions.

    The Risk: Falling Behind

    Opinion: The MBA in Finance Must Evolve—or Fade


    The Bottom Line: Is an MBA in Finance Worth It?

    An MBA in Finance isn’t for everyone. It’s a significant investment—in time, money, opportunity cost. But for the right professionals, it’s a career accelerator that can open doors to executive roles, higher salaries, cross-industry versatility.

    Here’s the final take:

    • If you’re aiming for leadership roles (e.g., CFO, VP of Finance), the MBA in Finance is the best degree for that trajectory.
    • If you’re switching industries (e.g., from tech to finance), the MBA’s broad business training makes it easier to pivot.
    • If you need strategic, not just analytical, skills, the MBA in Finance teaches you how to translate financial data into business strategy.
    • If you value versatility, the degree is valued in any sector, not just finance.

    But if you’re targeting technical roles (e.g., quant analyst, risk modeler), a Master of Finance might be a better fit. And if you’re not interested in leadership, the MBA’s broader perspective might not be worth the investment.

    The biggest question isn’t whether an MBA in Finance is valuable. It’s whether you’re ready to leverage it. The degree won’t guarantee success, but for those who use it strategically, it can be a game-changer.

    So: are you building a career in finance leadership—or just crunching numbers? That’s the real distinction.


  • **What Are Finance Charges in SBI Credit Cards? A Detailed Breakdown**

    **What Are Finance Charges in SBI Credit Cards? A Detailed Breakdown**

    Header image source: Business Credit Cards – Apply for Corporate Credit Card | SBI Card via SBI Card via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • SBI charges 3.5% monthly (42% annual) finance charges on unpaid balances
    • Finance charges apply from transaction date, even on partial payments
    • Pay full balance by due date to avoid charges; cash advances have no grace period

    3.5% per month. That’s the number staring back at you from your SBI credit card statement when you don’t clear the full balance by the due date. Not 3.5% per year—per month. Annualised, that’s 42%. Forty-two percent. Let that sink in. For context, personal loans typically cost 10–15% annually. Credit cards from other lenders often have similar annual rates. But SBI? 42%. And it starts accruing the day you swipe, not the day you miss payment.


    How SBI Bleeds You Dry: The Mechanics of Daily Compounding

    SBI doesn’t wait for your due date to start charging interest. The moment you make a purchase, the clock starts ticking. When you make a partial payment, the remaining balance continues to accrue finance charges. **At 3.5% monthly, finance charges accumulate quickly on unpaid balances. Unpaid finance charges themselves can accrue additional charges.

    The 3.5% monthly rate applies from the transaction date. No grace period for partial payments. Only for full payments. If you pay your balance in full, you may get an interest-free period on new purchases. Miss it, and the meter starts running.


    When Finance Charges Hit: Scenarios That Catch You Off Guard

    Finance charges aren’t just for late payments.

    1. Partial Payments: Pay ₹9,999 of a ₹10,000 bill? The entire ₹10,000 starts accruing interest, not just the ₹1 unpaid.
    2. Cash Advances: Withdraw ₹5,000 from an ATM using your SBI card, and finance charges apply immediately. No grace period. Cash advances accrue finance charges immediately at the same rate.
    3. Unpaid EMIs: Miss an EMI payment? The remaining installment amount starts accruing finance charges until it’s cleared.
    4. Refund Delays: A TechnoFino user reported being charged finance fees even after a refund was credited to their account. The refund took days to process, but the finance charges were calculated as if the balance was never reduced. SBI’s system doesn’t account for pending refunds in real time.

    The Hidden Costs: Why 42% Annual Interest Is a Financial Minefield

    • Personal loans typically range from 10–15% per annum.
    • Microfinance loans often have lower annual rates.
    • A ₹50,000 balance at 3.- A balance at 3.5% monthly can grow substantially if left unpaid. The interest accumulation can be substantial.

    Finance charges apply to all transactions until fully repaid. No partial relief. Partial payments mean the remaining balance continues to accrue finance charges.

    High outstanding balances can negatively impact your financial standing.


    Decoding the Jargon: What Does "FIN Charge on Retail" Even Mean?

    "FIN charge on Retail" isn’t a separate fee—it’s just finance charges applied to purchases. Cash advances accrue finance charges at the same 3.5% monthly rate.5% monthly**.

    Users frequently ask what "FIN charge on Retail" means. Many users assume it’s a penalty for retail transactions, not realising it’s just interest on unpaid purchases. SBI’s statements don’t make it obvious that these charges are avoidable if you pay your balance in full.


    How to Dodge Finance Charges: Strategies That Actually Work

    The only surefire way to avoid finance charges? Pay your full statement balance by the due date.

    1. 1. Grace Period: If you pay your balance in full, you may get an interest-free period on new purchases.
    2. 2. EMI Conversion: Converting purchases to EMIs may offer different payment terms.
    3. Avoid Cash Advances: Cash withdrawals start accruing interest immediately. No grace period.
    4. Track Refunds: If you’re expecting a refund, monitor your statement closely. Finance charges may still apply until the refund is fully processed.

    November’s Fee Update: What’s Changing (And What’s Not)

    SBI is revising its fee structure in November. The specifics on finance charges? Still unclear. New fee rules take effect in November, but whether finance charges will change is unclear.

    The current 3. If SBI bumps it to 3.6% monthly (43. If finance charges increase, users carrying balances will feel the impact. Changes to the fee structure could affect different users differently.


    The Complaints: Why Users Are Livid

    1. Refund-Related Charges: A TechnoFino user was charged finance fees even after a refund was credited to their account. The refund took days to process, but the finance charges were calculated as if the balance was never adjusted. SBI’s system doesn’t account for pending refunds in real time, leaving users to foot the bill for delays they didn’t cause.
    2. Lack of Transparency: Users struggle to understand how charges are applied and when they stop accruing. Statements don’t always make the calculation methodology clear. The "FIN charge on Retail" label adds to the confusion.

    Unlike purchases, which can be interest-free if paid in full, cash withdrawals start accruing interest the moment the transaction is made. This is standard across most banks, but SBI’s 3.5% monthly rate makes it particularly brutal.


    The Competition: How SBI Stacks Up Against Other Banks

    SBI’s **3.SBI’s 3.5% monthly finance charge is significant.

    • HDFC Bank: Up to 3.49% monthly (41.88% annually)—slightly lower than SBI.
    • ICICI Bank: 3.5% monthly (42% annually)—identical to SBI.
    • Axis Bank: 3.6% monthly (43.2% annually)—higher than SBI.

    A 0. Even small rate differences can add up over time. These differences accumulate significantly over time.

    Credit card finance charges in India can be substantial.


    The Big Question: Will SBI Ever Make Finance Charges Fairer?

    The future of credit card finance charges remains uncertain. The only surefire way to avoid it? Pay your balance in full, every time.


  • **What Is Financial Management?: A Strategic Framework for Resource Allocation, Growth, and Value**

    **What Is Financial Management?: A Strategic Framework for Resource Allocation, Growth, and Value**

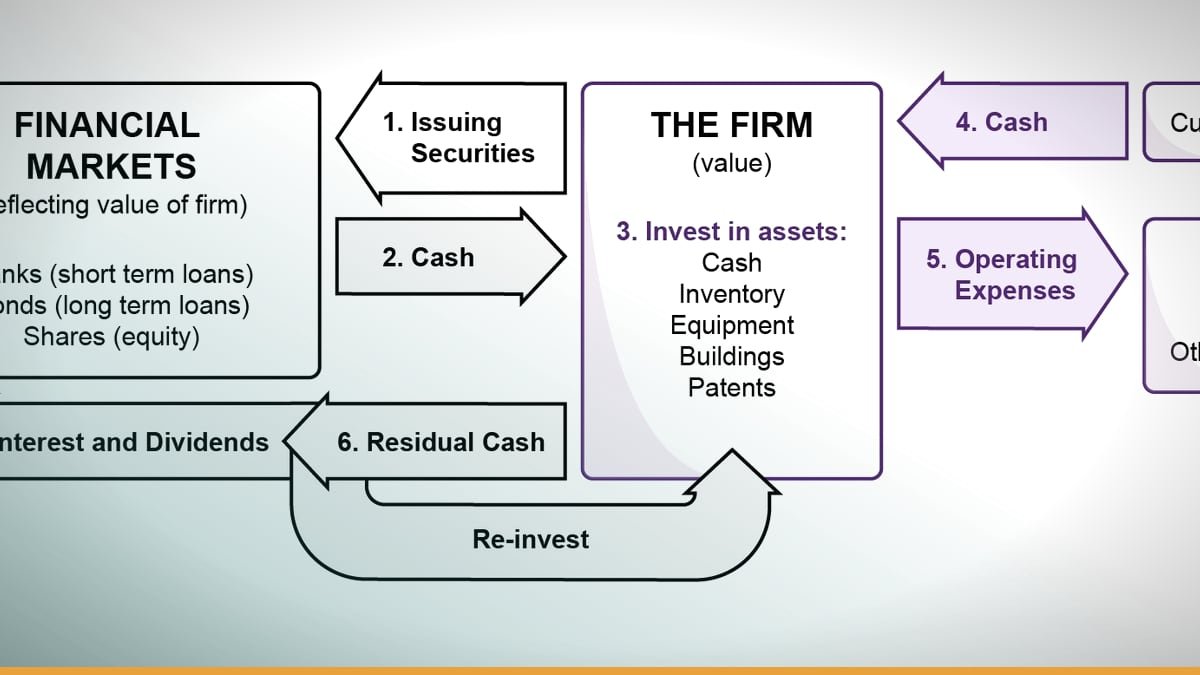
    Header image source: What is Financial Management? – Introduction to Financial Management: A Contemporary Approach via Open Textbooks @ UQ via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Financial management coordinates planning, organizing, directing and controlling money for growth
    • Four pillars guide decisions: resource allocation, investments, financing, and risk
    • Same principles apply to corporate and personal finance with different stakes

    Financial management isn’t just about counting money. It’s the deliberate, structured discipline of deciding where every dollar should go—whether that’s a $500 million corporate acquisition or a freelancer’s decision to pay off student loans instead of maxing out a Roth IRA. As one perspective puts it, finance is about getting funds, while financial management is about using them wisely for growth and success. That distinction matters. Financial management makes sure that capital is used effectively for growth and success.

    At its core, financial management operates through four interlocking functions: planning (setting targets like liquidity ratios or profit margins), organizing (structuring budgets and capital allocations), directing (guiding investment decisions and cost controls), and controlling (monitoring performance via variance analysis and compliance checks). These functions apply whether you’re a CFO evaluating a billion-dollar deal or an individual deciding between saving for a house or paying down credit card debt. The scale changes. The principles don’t.


    The Four Pillars: The Questions That Shape Every Financial Decision

    Financial management stands on four foundational pillars, each answering a critical question about how money moves through an organization or personal portfolio.

    1. Resource Allocation: Where Should Money Go?

    Resource allocation is the art of distributing limited funds across competing priorities. For a corporation, this might mean choosing between expanding into a new market or upgrading legacy IT systems. For an individual, it’s the trade-off between saving for a down payment or paying off high-interest credit card debt.

    The process hinges on cost-benefit analysis and opportunity cost—forcing decision-makers to quantify what they won’t get by choosing one path over another. A company allocating a portion of its budget to R&D might forgo short-term profits but position itself for long-term innovation. Tools like zero-based budgeting (justifying every dollar) or activity-based costing (linking expenses to specific outputs) help ensure allocations align with strategic goals.

    2. Investment Decisions: What Should We Fund?

    Investment decisions determine how capital generates future returns. Corporations evaluate projects using metrics like Net Present Value (NPV)—discounting future cash flows to their present value—or Internal Rate of Return (IRR), the break-even rate where an investment’s returns equal its cost. A project with a favorable IRR might get approved if it exceeds the company’s cost of capital, but rejected if it falls short.

    On the personal side, investment decisions revolve around asset allocation—the mix of stocks, bonds, real estate, and other vehicles in a portfolio. A younger person saving for retirement might tolerate a higher stock allocation for growth, while someone nearing retirement might shift to more conservative investments to reduce risk. Both scenarios rely on the same principle: maximizing return for a given level of risk.

    3. Financing Decisions: How Should We Fund Operations?

    Financing decisions revolve around a company’s capital structure—the mix of debt and equity used to fund operations and growth. Debt (loans, bonds) offers tax advantages—interest payments are tax-deductible—and avoids diluting ownership, but it comes with obligatory repayments that can strain cash flow. Equity (stock, retained earnings) doesn’t require repayment but dilutes control and may disappoint shareholders if returns fall short.

    Some financial theories suggest that, under certain conditions, capital structure doesn’t affect firm value. In reality, taxes, bankruptcy costs, and asymmetric information make the choice critical. Some companies might rely on equity to avoid debt payments, while others might issue debt to take advantage of favorable interest rates. The optimal structure balances cost of capital, financial flexibility, and risk tolerance.

    4. Risk Management: How Do We Protect Against Uncertainty?

    Risk management identifies, assesses, and mitigates financial threats—whether market volatility, liquidity crises, or operational failures. Corporations use hedging (e.g., futures contracts to lock in commodity prices) and diversification (spreading investments across industries) to reduce exposure. Individuals might rely on emergency funds (3–6 months of expenses) or insurance (health, disability, life) to protect against unexpected shocks.

    Historical financial crises have demonstrated the consequences of poor risk management. Some financial institutions became overleveraged, assuming certain asset prices would remain stable. When market conditions deteriorated, liquidity dried up, and some institutions collapsed. Today, Value at Risk (VaR) models and stress testing help quantify potential losses under adverse scenarios, but no tool can eliminate risk entirely—only manage it.


    Corporate vs. Personal Financial Management: Same Rules, Different Stakes

    The core principles of financial management apply universally, but the goals and tools differ between corporate and personal contexts.

    Corporate Financial Management

    Primary Goal: Maximize shareholder (or stakeholder) value. Key Tools:

    • Financial statements: Balance sheets (assets = liabilities + equity), income statements (revenue – expenses = profit), and cash flow statements (operating, investing, financing activities).
    • KPIs: EBITDA, ROIC (return on invested capital), and current ratio (liquidity).
    • Capital budgeting: Evaluating long-term investments (e.g., building a new factory) using NPV, IRR, or payback period.

    Example: A CFO might decide to issue bonds to fund expansion projects. The decision hinges on weighing the cost of debt (interest payments) against the potential ROI from increased production capacity.

    Personal Financial Management

    Primary Goal: Achieve individual milestones (retirement, homeownership, education). Key Tools:

    • Budgets: Tracking income and expenses (e.g., the 50/30/20 rule: 50% needs, 30% wants, 20% savings).
    • Investment accounts: 401(k)s, IRAs, brokerage accounts, and 529 plans (education savings).
    • Debt management: Strategies like the avalanche method (paying off high-interest debt first) or snowball method (paying off small balances first for psychological wins).

    Example: A financial planner might advise a client to maximize retirement contributions to reduce taxable income, then allocate remaining savings to other investment accounts for flexibility.

    Overlap and Divergence

    Both domains rely on cash flow management, risk assessment, and goal alignment, but the scale and consequences differ. A corporation’s poor investment decision might wipe out billions in market value; an individual’s might delay retirement by a decade. Yet the frameworks—like the time value of money (a dollar today is worth more than a dollar tomorrow)—remain identical.


    The Capital Structure Decision: Debt vs. Equity, and Everything in Between

    One of the most consequential decisions in financial management is determining a company’s capital structure—the mix of debt and equity used to finance operations. This choice affects everything from profitability to bankruptcy risk.

    Key Considerations

    1. Cost of Capital:
    • Debt is cheaper than equity because interest payments are tax-deductible, reducing a company’s taxable income. A 6% interest rate on debt might effectively cost only 4% after tax savings (assuming a 33% tax rate).
    • Equity is more expensive because investors demand higher returns to compensate for risk. The Capital Asset Pricing Model (CAPM) calculates the cost of equity as:

    “ Cost of Equity = Risk-Free Rate + Beta × (Market Return – Risk-Free Rate) “ A company with a beta of 1.5 (50% more volatile than the market) might have a cost of equity of 12%, far higher than its cost of debt.

    1. Financial Leverage:
    • Leverage amplifies returns—but also losses. A company with balanced financing between debt and equity has a debt-to-equity ratio of 1. If assets generate returns above the cost of debt, equity holders can earn amplified returns. But if assets underperform, equity holders can experience amplified losses.
    1. Flexibility vs. Control:
    • Debt avoids dilution but comes with covenants (e.g., maintaining a minimum current ratio) that can restrict operations.
    • Equity doesn’t require repayment but dilutes ownership. Founders of a startup might see their ownership stake diluted after multiple funding rounds.

    Optimal Capital Structure

    There’s no one-size-fits-all answer, but industries tend to cluster around norms:

    • Capital-intensive industries (utilities, airlines) use more debt to fund infrastructure.

    Some companies rely on equity to avoid debt payments during growth phases. Mature firms often use a mix of financing options, balancing tax advantages with financial flexibility.

    The pecking order theory suggests companies prefer internal financing (retained earnings) first, then debt, and equity as a last resort. This hierarchy reflects the information asymmetry between managers and investors—issuing equity can signal that a company’s stock is overvalued.


    Tools and Techniques: How Financial Management Gets Done

    Financial management isn’t theoretical. It’s executed through concrete tools and techniques that turn strategy into action.

    Financial Planning

    Financial planning involves forecasting revenue, expenses, and cash flow to guide decision-making. Corporations use rolling budgets (updated monthly or quarterly) and scenario analysis (best-case, worst-case, most-likely outcomes) to prepare for uncertainty. A company might model sales under various scenarios, adjusting operations accordingly.

    Key Tools:

    • Pro forma statements: Projected financial statements based on assumptions about future performance.
    • Cash flow forecasting: Predicting inflows (revenue, loans) and outflows (expenses, debt repayments) to avoid liquidity crises.

    Performance Monitoring

    Once plans are in place, performance must be tracked to ensure alignment with goals. Variance analysis compares actual results to budgets, identifying deviations (e.g., higher-than-expected marketing costs). Dashboards (Power BI, Tableau) visualize KPIs in real time, allowing managers to spot trends or anomalies quickly.

    Key Metrics:

    • Working capital: Current assets – current liabilities (measures short-term liquidity).
    • Profit margins: Gross margin (revenue – COGS), operating margin (EBIT/revenue), net margin (net income/revenue).
    • Return on assets (ROA): Net income / total assets (measures efficiency in generating profits from assets).

    Compliance and Reporting

    Financial management ensures adherence to regulations (GAAP, IFRS) and transparency for stakeholders. Public companies file 10-K reports (annual) and 10-Q reports (quarterly) with the SEC, detailing financial performance and risks. Private companies might produce management accounts for internal use, focusing on metrics like EBITDA.

    Financial management software can automate compliance reporting, reducing errors and saving time. Features like automated reconciliations and audit trails ensure accuracy and accountability.

    Technology’s Role

    Technology has transformed financial management from a manual, spreadsheet-driven process to a real-time, data-driven discipline. Enterprise Resource Planning (ERP) systems (SAP, Oracle) integrate financial data with operations, supply chain, and HR, providing a holistic view of the business. AI and machine learning enhance forecasting, fraud detection, and investment analysis.

    AI-driven predictive analytics can forecast business trends, allowing companies to make proactive decisions. Robotic Process Automation (RPA) handles repetitive tasks like invoice processing, freeing finance teams for strategic work.


    The Human Element: Skills and Careers in Financial Management

    Financial management isn’t just about numbers. It’s about people. The field demands a mix of technical expertise, strategic thinking, and leadership to guide organizations or individuals toward financial success.

    Education and Certifications

    • Minimum: A bachelor’s degree in finance, economics, accounting, or business. Coursework covers financial accounting, corporate finance, investments, and statistics.
    • Advanced: An MBA or specialized certifications like:
    • CFA (Chartered Financial Analyst): Focuses on investment management.
    • CPA (Certified Public Accountant): Emphasizes accounting and auditing.
    • FP&A (Financial Planning & Analysis) Certification: Targets corporate financial planning.

    Example: A financial analyst might hold professional certifications, while other finance professionals might have different credentials.

    Key Skills

    1. Technical Skills:
    • Financial modeling: Building Excel models to project financial performance.
    • Data analysis: Using SQL, Python, or R to extract insights from large datasets.
    • Regulatory knowledge: Understanding GAAP, IFRS, and industry-specific rules (e.g., Basel III for banks).
    1. Soft Skills:
    • Leadership: Managing teams, influencing stakeholders, and driving change.
    • Communication: Translating complex financial data into actionable insights for non-experts.
    • Strategic thinking: Aligning financial decisions with long-term business goals.

    Career Paths

    Financial management careers span corporate, personal, and public sectors:

    | Role | Responsibilities | Typical Salary (U.S.) | |————————-|————————————————————————————-|—————————| | $60,000–$90,000 | | $90,000–$150,000 | | $120,000–$200,000 | | $200,000–$500,000+ | | $60,000–$150,000 | | $100,000–$300,000 |

    Upper-level roles typically require significant experience in finance or management. Entry-level positions (financial analyst) often start with internships or rotational programs.


    Why Financial Management Matters: Outcomes and Impact

    Financial management isn’t an abstract exercise. It’s the backbone of stability, growth, and value creation for businesses and individuals alike.

    For Businesses

    1. Stability: Ensures liquidity to meet payroll, supplier payments, and debt obligations. A company with poor cash flow management might face operational challenges.
    2. Profitability: Optimizes revenue streams and cost structures. Business strategies rely on financial management to allocate resources efficiently.
    3. Growth: Funds innovation, expansions, and acquisitions. Company growth often requires disciplined capital allocation across different business areas.
    4. Stakeholder Value: Aligns decisions with shareholder interests. Shareholder theory argues that a company’s sole responsibility is to maximize profits, while stakeholder theory broadens the focus to employees, customers, and communities.

    Example: During economic challenges, companies with strong financial management tend to fare better than those with weak financial positions.

    For Individuals

    1. Security: Builds emergency funds (3–6 months of expenses) and retirement savings. Research has shown that many individuals struggle with emergency expenses, highlighting the importance of financial management.
    2. Opportunity: Enables investments (stocks, real estate, education) and debt reduction. Compound interest turns small, consistent savings into significant wealth over time. Consistent investing over time can grow savings significantly through compound returns.
    3. Freedom: Reduces financial stress by providing clarity and control. Behavioral finance shows that people with financial plans are happier and less anxious about money.

    Some financial approaches demonstrate how aggressive savings and disciplined investing can achieve financial independence.

    Societal Impact

    Efficient financial management drives economic growth by directing capital to its most productive uses. Venture capital funds startups (e.g., Uber, Airbnb), while bond markets finance infrastructure (bridges, schools). Poor financial management can contribute to economic downturns.


    Common Misconceptions and Pitfalls

    Financial management is often misunderstood, leading to costly mistakes.

    Reality: Accounting records past transactions; financial management shapes the future. Accounting asks, "What happened?" Accounting focuses on recording past transactions, while financial management focuses on planning for the future. An accountant might report changes in revenue performance. A financial manager would analyze performance and recommend appropriate actions.

    Reality: Small businesses and individuals rely on financial management daily. A freelancer tracking cash flow, a startup securing seed funding, or a family budgeting for college—all engage in financial management. Cash flow management is especially critical for small businesses, as many failures relate to cash flow issues.

    Pitfall 1: Overleveraging

    Excessive debt can lead to insolvency. Some financial crises have been fueled by excessive leverage in the banking system. When asset prices fell significantly, some institutions couldn’t cover losses, triggering broader financial problems.

    Lesson: The debt-to-equity ratio should align with industry norms and risk tolerance. A common guideline suggests that total debt should be kept within reasonable limits relative to equity.

    Pitfall 2: Short-Termism

    Prioritizing quarterly profits over long-term sustainability destroys value. Some companies have failed to adapt to technological changes despite having early advantages. Some companies have failed to adapt to market disruptions, allowing competitors to dominate. Both collapsed.

    Lesson: Discounted Cash Flow (DCF) models force companies to consider long-term value, not just immediate gains.

    Pitfall 3: Ignoring Risk

    The 2008 crisis and COVID-19 pandemic proved that "black swan" events happen. Companies without contingency plans or diversified revenue streams fail. Example: Companies with strong financial positions tend to survive economic challenges better than those with high debt levels.

    Lesson: Stress testing and scenario planning prepare for worst-case scenarios.


    The Future of Financial Management: Trends to Watch

    Financial management is evolving rapidly, driven by technology, globalization, and shifting priorities.

    AI and Automation

    AI is transforming financial management from descriptive (what happened) to prescriptive (what should happen). Key applications:

    • Fraud detection: Machine learning models identify anomalous transactions in real time.
    • Predictive analytics: Forecasting cash flow, demand, and market trends with greater accuracy.
    • Algorithmic trading: AI-driven investment approaches can generate returns by analyzing large datasets.

    Some financial institutions use AI to review documents, reducing errors and saving time.

    Sustainability Integration

    ESG (Environmental, Social, Governance) metrics are reshaping investment decisions. Companies with strong ESG scores attract capital, while laggards face higher costs. Example: Some asset managers now evaluate companies on ESG performance. Green bonds fund renewable energy and other sustainable projects.

    Challenge: Measuring ESG impact is subjective. Greenwashing—exaggerating sustainability efforts—is a growing concern.

    Decentralized Finance (DeFi)

    Blockchain and smart contracts are enabling peer-to-peer lending, trading, and insurance without intermediaries. Example: Decentralized exchanges allow users to trade cryptocurrencies without central authorities. DeFi lending platforms allow users to earn interest on deposits.

    Risks: Regulatory uncertainty, security vulnerabilities (e.g., $600 million Poly Network hack), and volatility.

    Personalization

    Robo-advisors use algorithms to create personalized investment portfolios based on risk tolerance and goals. Example:

    • An investor with high risk tolerance might get a higher stock allocation.
    • An investor nearing retirement might get a more conservative allocation.

    Challenge: Robo-advisors lack the human touch—critical for complex financial planning (e.g., tax strategies, estate planning).


    The Open Question: Can Financial Management Keep Up?

    Financial management has always been about balancing risk and return, but the stakes are higher than ever. Climate change, geopolitical instability, and technological disruption demand new tools and mindsets. Can traditional frameworks adapt to a world where intangible assets comprise significant market value? Can regulators keep pace with DeFi’s borderless, algorithm-driven transactions?

    The most pressing question isn’t whether financial management will evolve. It’s how fast it can evolve to meet the challenges of the 21st century. The answer will determine who thrives and who gets left behind.


  • **What Is a Finance Job? A Data-Driven Breakdown of Roles, Impact, and Career Realities**

    **What Is a Finance Job? A Data-Driven Breakdown of Roles, Impact, and Career Realities**

    Header image source: What is a Project Breakdown Structure? – The Results-Driven Microsoft Partner for Project-Centric Enterprises via Adeaca via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Finance jobs span five core sectors with vastly different salaries, work cultures, and career paths.
    • Investment banking offers the highest pay but demands extreme hours; corporate finance provides stability.
    • Technical skills like financial modeling are essential, but communication and storytelling differentiate top performers.

    A Data-Driven Breakdown of Roles, Impact, and Career Realities**

    A finance job isn’t one thing. It’s a sprawling ecosystem of roles—some glamorous, some grueling, some invisible—that all revolve around money, risk, and decision-making. Budget analysts forecast cash flows. Investment bankers price billion-dollar deals. Financial planners talk clients through retirement. The common thread? Finance professionals don’t just track money—they shape its future.

    The confusion around "what is a finance job" comes from its sheer breadth. It’s not a single career but a toolkit of skills applied across industries with wildly different cultures, pay scales, and work-life balances. The data confirms this: while finance jobs share analytical rigor and strategic thinking, their daily realities diverge sharply depending on the sector, education, and organizational goals. Let’s cut through the noise.


    The Five Core Sectors: Where Finance Jobs Live (And Why It Matters)

    Finance clusters into five primary sectors. These aren’t rigid silos—professionals move between them—but the differences define careers.

    1. Commercial Banking: The Risk Assessors

    Commercial banking is where finance meets Main Street. Loan officers evaluate creditworthiness. Credit analysts model default probabilities. Branch managers oversee operations. These roles are transactional and client-facing, often serving as the first point of contact for businesses seeking capital.

    Commercial banking is foundational to finance. Many finance professionals start here before pivoting elsewhere. It’s less volatile than investment banking—steadier hours, lower stress—but the compensation reflects that. The upside is capped.

    2. Corporate Finance: The Internal Strategists

    Corporate finance professionals operate inside companies, managing budgets, investments, and financial strategy. CFOs, treasurers, and financial analysts fall into this bucket. Their work is operational and long-term: forecasting cash flow, optimizing capital structure, advising on mergers.

    Corporate finance focuses on internal decision-making. A financial analyst at a tech company might spend weeks modeling the ROI of a new product line. A treasurer ensures liquidity for payroll. These roles lack the glamour of investment banking but offer stability and work-life balance.

    3. Investment Banking: The Deal Makers

    Investment banking is finance’s high-stakes arena. Jobs here revolve around raising capital, mergers, and acquisitions. Underwriters price IPOs. M&A advisors structure billion-dollar deals. Investment banking roles are client-facing and strategic, but the reality is brutal hours and intense pressure.

    Compensation reflects the demands. Entry-level analysts at bulge-bracket banks (Goldman Sachs, JPMorgan) earn $150K+ in their first year, including bonuses. But the trade-off is 80-100 hour weeks and a career path that burns out many before they reach the top.

    4. Financial Planning: The Client Advocates

    Financial planners work one-on-one with individuals to manage wealth, retirement, taxes, and estate planning. Certified Financial Planners (CFPs) help clients navigate everything from college savings to tax optimization. Financial planning roles are satisfying because they help people achieve financial goals—a stark contrast to the transactional nature of investment banking.

    The downside? Lower pay than corporate or investment roles (median salary: ~$95K) and heavy reliance on client relationships. Success here depends on trust and communication, not just technical skills.

    5. Retail Banking: The Frontline Workers

    Retail banking includes consumer-facing roles like tellers, personal bankers, and mortgage advisors. These jobs are transactional and service-oriented: processing deposits, opening accounts, selling financial products like credit cards or loans.

    It’s not a career destination for most finance professionals. Compensation is modest (median salary: ~$36K for tellers), and automation is rapidly reducing demand for entry-level roles. That said, it’s a low-barrier entry point for those without a finance degree.


    The Daily Work: What Finance Professionals Actually Do

    Finance jobs involve helping people work through financial problems. The reality is that daily work varies dramatically by role. Here’s what professionals in each sector actually do:

    Client-Facing Roles: Relationships Over Spreadsheets

    Financial planners and investment bankers build relationships first, crunch numbers second. A CFP might spend hours with a client diagnosing their retirement shortfall, then craft a tailored plan involving Social Security timing, Roth conversions, and annuities. An M&A advisor pitches potential buyers on why their client’s company is a strategic fit—then spends nights modeling synergies.

    These roles help people achieve their financial goals. But it’s not altruistic. Financial planners earn commissions on products they sell. Investment bankers take a cut of deals they close. The work is advisory, but the incentives are transactional.

    Analytical Roles: Data as the Product

    Budget analysts, corporate finance analysts, and risk managers live in Excel and PowerPoint. Their work is repetitive but critical: tracking variances, updating forecasts, flagging anomalies. A budget analyst at a university might spend weeks reconciling departmental spending against allocations. A risk manager at a hedge fund models Value-at-Risk (VaR) for a portfolio.

    These roles involve organizing and planning finances. The best analysts automate what they can (VBA, Python) and focus on insights, but the job still involves endless data hygiene.

    Strategic Roles: Decisions Over Execution

    CFOs, treasurers, and investment committee chairs shape policy and allocate capital. Their work is high-level and long-term: Should the company issue debt or equity? Is a merger accretive to earnings? How much should we return to shareholders via buybacks?

    These roles involve formulating policies. A CFO’s recommendation on capital allocation can make or break a company’s future. But the work is less about technical finance and more about stakeholder management—convincing the board, aligning with the CEO, navigating investor expectations.

    Technical Roles: The Hidden Engine

    Risk analysts, portfolio managers, and quants build the models that drive decisions. Their work is highly specialized: Monte Carlo simulations for pension funds, factor models for asset managers, stress tests for banks.

    A portfolio manager’s algorithm might determine billions in asset allocation. A risk analyst’s model could prevent a bank from collapsing—or fail spectacularly, as in the 2008 crisis. These jobs reward deep expertise but are less visible than client-facing roles.


    Compensation and Career Trajectories: What the Numbers Reveal

    Finance jobs offer high-paying salaries depending on education. Here’s the reality:

    Entry-Level Pay: The Education Premium

    • Bachelor’s degree: Entry-level roles (financial analyst, credit analyst) start at $60K–$80K.
    • Master’s degree (MBA, MS Finance): $100K–$150K for roles like associate in investment banking or corporate finance.
    • Certifications: CFA, CPA, or CFP holders earn 10–20% more than peers without them.

    A master’s degree provides an advantage in the finance job market. At top MBA programs (Wharton, Booth), 95%+ of graduates land finance jobs with six-figure starting salaries. The ROI on education is clear but expensive—tuition at these schools exceeds $200K.

    Advancement: The Pyramid Structure

    Finance careers follow a pyramid model:

    1. Entry-level (0–3 years): Analysts, associates—grunt work (Excel, PowerPoint, due diligence).
    2. Mid-level (3–7 years): Managers, VPs—client-facing, leading teams.
    3. Senior-level (7–15 years): Directors, MDs—strategic, closing deals.
    4. C-suite (15+ years): CFO, CEO—visionary, setting direction.

    Finance careers offer opportunities for advancement. In investment banking, only 10–20% of analysts make it to MD. Corporate finance is more stable, but promotions slow after director level.

    Compensation by Sector: The Winners and Losers

    | Sector | Entry-Level Salary | Mid-Career Salary | Peak Earnings | |———————-|——————–|——————-|———————| | Investment Banking | $150K–$200K | $300K–$500K | $1M–$10M+ (MDs) | | Corporate Finance | $70K–$100K | $150K–$250K | $500K–$2M (CFOs) | | Financial Planning | $50K–$70K | $100K–$150K | $200K–$500K (Top CFPs) | | Commercial Banking | $50K–$80K | $100K–$150K | $200K–$400K (Regional CEOs) | | Retail Banking | $30K–$50K | $50K–$80K | $100K–$200K (Branch Execs) |

    Includes bonuses.

    Investment banking pays 10x more than retail banking at the peak. But the trade-offs—hours, stress, job security—are just as stark.

    Benefits: The Hidden Perks

    Finance jobs often come with lucrative benefits:

    • Retirement packages: 401(k) matches, pension plans (rare but still exist in some firms).
    • Stock options: Common in corporate roles (e.g., tech companies) and investment banking (bonuses often paid in stock).
    • Signing bonuses: $20K–$50K for top MBA hires.
    • Perks: Private banking clients get VIP treatment (concert tickets, luxury travel), while senior bankers enjoy expense accounts and club memberships.

    Finance jobs commonly offer benefits such as retirement packages and stock options. These benefits compound over time, especially in corporate roles where equity grants can turn into life-changing wealth.


    The Skills That Matter: What Finance Jobs Really Demand

    Finance courses provide knowledge of financial insight, technology, and interpersonal skills. Here’s what actually separates top performers:

    Technical Skills: The Non-Negotiables

    1. Financial Modeling: Building three-statement models (income statement, balance sheet, cash flow) is table stakes. Investment bankers live in DCF (Discounted Cash Flow) models; corporate finance analysts rely on budgeting and forecasting.
    2. Data Analysis: Proficiency in Excel (advanced functions, pivot tables, VBA) and Python (Pandas, NumPy) is increasingly required. Finance courses provide knowledge of technology.
    3. Regulatory Knowledge: Understanding GAAP, IFRS, and Basel III (for banks) is critical. Compliance roles grew 30% post-2008, and the trend isn’t slowing.
    4. Valuation: Methods like comparable company analysis (comps), precedent transactions, and LBO (Leveraged Buyout) modeling are sector-specific. An M&A banker needs all three; a financial planner might only need basic valuation.

    Soft Skills: The Differentiators

    1. Client Communication: Explaining complex ideas simply is more valuable than technical skill. A financial planner who can’t build trust won’t retain clients. An investment banker who can’t pitch won’t close deals.
    2. Negotiation: Whether it’s pricing a bond issue or advising on a merger, finance professionals constantly negotiate. The best understand psychology—what the other side really wants.
    3. Finance jobs involve building relationships with clients. Finance is a networking industry. Who you know often matters more than what you know.
    4. Storytelling: Data is useless without narrative. A CFO who can’t tell the story behind the numbers won’t sway the board. An equity analyst who can’t craft a thesis won’t move the stock.

    Sector-Specific Expertise: The X-Factors

    • Investment Banking: M&A process knowledge, pitchbook creation, deal execution.
    • Corporate Finance: Capital budgeting, working capital management, investor relations.
    • Financial Planning: Tax law, estate planning, insurance products.
    • Risk Management: Derivatives pricing, stress testing, regulatory reporting.

    Finance courses provide knowledge essential for job market success. Real-world experience—internships, on-the-job training—matters just as much. A CFA charterholder with no client experience will struggle in financial planning. An Excel whiz with no deal experience won’t survive in investment banking.


    The Hidden Trade-Offs: Stress, Satisfaction, and Job Security

    Finance careers look glamorous from the outside, but the brief’s rosy picture of "satisfying" work and "opportunities for advancement" ignores the dark side. Here’s what the data doesn’t always show:

    Job Satisfaction: The Paradox

    Finance careers are satisfying because they allow professionals to help people. But satisfaction varies wildly:

    • High: Financial planners (70%+ satisfaction), corporate finance (60%).
    • Low: Investment banking (<40%), retail banking (<50%).

    The biggest driver of dissatisfaction? Work-life balance. Investment bankers routinely work 80+ hours/week. Corporate finance roles are better (50–60 hours), but deadlines (quarter-end, budget season) spike stress. Financial planners have more control over their schedules, but client demands can be unpredictable.

    Work-Life Balance: The Unspoken Cost

    | Role | Avg. Hours/Week | Work-Life Balance Rating (1–10) | |———————|—————–|———————————-| | Investment Banker | 80–100 | 2 | | Corporate Finance | 50–60 | 6 | | Financial Planner | 40–50 | 8 | | Commercial Banker | 40–50 | 7 | | Retail Banker | 35–45 | 6 |

    Investment banking’s grueling schedule is well-documented, but even corporate finance has crunch times (quarter-end, budget season). Financial planners set their own hours, but client emergencies can disrupt evenings and weekends.

    Job Security: The Automation Risk

    Finance careers offer opportunities for advancement. Roles heavily reliant on repetitive tasks are most at risk:

    • High risk: Retail banking (tellers, loan processors), basic financial analysis (data entry, report generation).
    • Low risk: Client-facing roles (financial planners, investment bankers), strategic roles (CFOs, treasurers).

    The safest jobs are those requiring judgment, relationships, or complex problem-solving. A robo-advisor can rebalance a portfolio, but it can’t build trust with a grieving widow. A Python script can pull financials, but it can’t negotiate a merger.

    Career Longevity: The Marathon, Not the Sprint

    Finance knowledge plays a key role in formulating policies in finance-related jobs. Early-career burnout is rampant in high-pressure sectors like investment banking and trading. Many pivot to corporate finance or fintech after 5–10 years.

    The longest careers are in:

    • Corporate finance (stable, less volatile).
    • Financial planning (client relationships compound over time).
    • Regulatory/compliance (growing demand).

    The shortest careers are in:

    • Investment banking (attrition after 3–5 years).
    • Trading (high stress, age discrimination).

    The Future of Finance Jobs: Trends Shaping the Field

    Finance courses provide knowledge of technology. Finance is undergoing a seismic shift, and the jobs of the future won’t look like today’s. Here’s what’s changing:

    Technology: The Double-Edged Sword

    1. Automation: Repetitive tasks (data entry, report generation, basic analysis) are being automated. Tools like RPA (Robotic Process Automation) and AI (e.g., Kensho, AlphaSense) are replacing entry-level roles.
    • Impact: Fewer junior analysts needed. More demand for data scientists who can train models.
    1. AI and Machine Learning: Predictive analytics is replacing gut instinct. Hedge funds use alternative data (satellite imagery, credit card transactions) to beat the market.
    • Impact: Quants (quantitative analysts) are in high demand. Traditional fundamental analysts are struggling.
    1. Blockchain and DeFi: Decentralized finance is disrupting traditional banking. Smart contracts eliminate intermediaries (e.g., loans, insurance).
    • Impact: Commercial banks face existential threats. Fintech startups are hiring aggressively.

    Finance courses provide knowledge of technology. Coding (Python, SQL) is now a core skill. Universities are adding fintech tracks, but most professionals will need self-directed learning to keep up.

    Regulation: The Compliance Boom

    Post-2008, financial regulations (Dodd-Frank, Basel III, MiFID II) quadrupled in complexity. The cost of compliance for banks exceeds $100B annually.

    • Impact: Compliance and risk management jobs are growing 10%+ per year.
    • Opportunity: Regulatory technology (RegTech) startups are hiring to automate compliance.

    A risk analyst at a bank now has more job security than a trader.

    Globalization: The Borderless Market

    Finance is increasingly global. Multinational corporations operate in 50+ countries. Emerging markets (China, India, Africa) are growing faster than developed economies.

    • Impact: Cross-border expertise is in demand. Roles like international treasurer and emerging market analyst are growing.
    • Challenge: Geopolitical risk (trade wars, sanctions) adds complexity.

    An education in finance can prepare individuals for a range of industries and job settings. Global finance requires cultural fluency—not just technical skills.

    Demographics: The Aging Workforce

    The finance industry is graying. 40% of financial advisors are over 55. 20% of investment bankers are over 50.

    • Impact: Massive hiring wave coming as Baby Boomers retire.
    • Opportunity: Young professionals can leapfrog into senior roles faster than in the past.

    How to Break Into Finance: What the Evidence Recommends

    There are myriad career options in finance that increase with more education and on-the-job experience. Here’s what actually works:

    Education: The Foundation (But Not the Finish Line)

    1. Bachelor’s Degree: Minimum requirement for most roles. Top majors:
    • Finance (obvious choice).
    • Economics (strong alternative).
    • Accounting (for corporate finance).
    • STEM (for quant roles—math, physics, computer science).
    1. Master’s Degree: Accelerates careers. Best options:
    • MBA (for corporate finance, investment banking).
    • MS Finance (for quantitative roles).
    • Master’s in Financial Engineering (for quant funds).
    1. Certifications: Signal expertise. Most valuable:
    • CFA (Chartered Financial Analyst): Gold standard for investment management.
    • CPA (Certified Public Accountant): Essential for corporate finance.
    • CFP (Certified Financial Planner): Required for financial planning.
    • FRM (Financial Risk Manager): Growing in risk management.

    A master’s degree in finance provides an advantage in the finance job market. A top-10 MBA (Harvard, Stanford) opens doors. A no-name MS Finance might not.

    Experience: The Catch-22

    Finance is notoriously competitive. Breaking in requires:

    1. Internships: Non-negotiable for top roles. Summer analyst programs (investment banking, corporate finance) are the best path.
    • Where to target: Bulge-bracket banks (Goldman, JPMorgan), Big 4 accounting firms (PwC, Deloitte), Fortune 500 companies.
    1. Entry-Level Jobs: First roles matter. Best options:
    • Financial Analyst (corporate finance).
    • Investment Banking Analyst (highest upside, highest stress).
    • Credit Analyst (commercial banking).
    • Wealth Management Associate (financial planning).
    1. Networking: 80% of finance jobs are filled through referrals. How to network:
    • Alumni connections (LinkedIn, university career services).
    • Industry events (CFA society meetings, finance conferences).
    • Informational interviews (ask for advice, not jobs).

    Finance careers offer the ability to obtain jobs quickly. Competition is fierce. Even top-tier MBA grads struggle to land investment banking jobs without prior experience.

    Skills: The Differentiators

    1. Technical Skills:
    • Excel: Advanced functions (XLOOKUP, INDEX-MATCH), pivot tables, VBA.
    • PowerPoint: Pitchbook creation (investment banking), board presentations (corporate finance).
    • Python/SQL: Data analysis, automation.
    1. Soft Skills:
    • Communication: Clear, concise, persuasive.
    • Networking: Genuine relationships, not transactional.
    • Resilience: Finance is high-pressure. Burnout is real.

    Finance courses provide knowledge of interpersonal skills. Technical skills get you in the door. Soft skills keep you climbing.

    Mindset: The X-Factor

    Finance rewards certain personalities:

    • Competitive: Investment banking, trading.
    • Analytical: Corporate finance, risk management.
    • Client-Focused: Financial planning, private banking.
    • Entrepreneurial: Fintech, hedge funds.

    If you hate sales, avoid client-facing roles. If you hate Excel, avoid analytical roles.


    The Bottom Line: Is a Finance Job Right for You?

    Finance isn’t a monolith. It’s a spectrum of roles with different purposes, payoffs, and trade-offs. Finance jobs help people achieve their financial goals.

    Choose Finance If You…

    ✅ Enjoy problem-solving (finance is applied puzzle-solving). ✅ Like working with numbers (but not necessarily accounting). ✅ Want influence (finance professionals shape decisions at every level). ✅ Thrive in high-pressure environments (some roles demand it). ✅ Value career mobility (finance skills transfer across industries).

    Avoid Finance If You…

    ❌ Hate ambiguity (finance is not black-and-white). ❌ Dislike sales (many roles require pitching). ❌ Want work-life balance (some sectors demand 80+ hours/week). ❌ Prefer stability (markets crash, bonuses disappear). ❌ Can’t handle stress (finance is high-stakes).

    The Key Question: What Kind of Finance Job?

    Finance jobs divide into three broad categories:

    1. Advisory: Helping clients (financial planning, investment banking).
    • Pros: High satisfaction, client relationships.
    • Cons: Lower pay (financial planning), high stress (investment banking).
    1. Analytical: Crunching numbers (corporate finance, risk management).
    • Pros: Stable, less client-facing.
    • Cons: Repetitive, less glamorous.
    1. Executive: Shaping strategy (CFO, treasurer, portfolio manager).
    • Pros: High pay, influence.
    • Cons: Long hours, high pressure.

    Finance jobs offer the chance to move between different areas of interest within the finance field. Skills transfer. Networks compound. Experience opens doors. But success requires alignment—with your strengths, your values, and your risk tolerance.

    So, what is a finance job? It’s whatever you make of it. A lucrative grind in investment banking. A stable career in corporate finance. A fulfilling calling in financial planning. The field is broad enough to fit almost anyone—but only if you choose wisely.

    The real question isn’t whether finance is right for you. It’s which version of finance you’re built for.


  • **What Is a Finance Bill?: The Legislative Engine of Fiscal Policy**

    **What Is a Finance Bill?: The Legislative Engine of Fiscal Policy**

    Header image source: About Finance Bill – UPSC Current Affairs – IAS GYAN via IAS Gyan via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • A Finance Bill converts budget tax proposals into enforceable law
    • Money Bills bypass Rajya Sabha amendment powers
    • Finance Bills enable retrospective tax changes and GST amendments

    A Finance Bill is what turns a budget speech into tax law. When the finance minister announces a new income-tax slab or a hike in customs duty, those proposals stay just that—proposals—until they’re written into a Finance Bill, debated in Parliament, and signed into law. Without it, the government can’t collect a single rupee in new taxes. It’s the difference between a fiscal wish-list and fiscal reality.

    Its definition is precise: a legislative instrument that grants certain duties, alters other duties, and amends the law relating to the National Debt and the Public Revenue. Every year, the Finance Bill consolidates every tax change the government wants—GST tweaks, new levies on digital transactions, whatever—and packages them into one sprawling document. Once Parliament approves it and the President assents, it becomes the Finance Act, and its provisions snap into force. That’s the point: to convert budget resolutions into binding statute.


    How a Finance Bill Is Born

    The Finance Bill doesn’t appear out of nowhere. It’s the legislative endpoint of a process that starts with the budget speech. After the finance minister delivers the budget, Parliament debates its proposals and passes budget resolutions—formal decisions approving tax changes in principle. Those resolutions aren’t law. They’re political statements. The Finance Bill gives them legal teeth.

    In India, the Constitution says Finance Bills can only be introduced in the Lok Sabha. This isn’t just procedure. It reflects the principle that the people’s directly elected representatives should have the final say on taxation. The Rajya Sabha plays a secondary role. If the Finance Bill is a Money Bill under Article 110, the Rajya Sabha can’t amend it at all—only make non-binding recommendations. If it’s a regular Finance Bill, the Rajya Sabha can propose amendments or even reject it, but the Lok Sabha can override those objections.

    Its clauses mirror the tax proposals announced in the budget, but with the legal precision needed for enforcement. If the budget proposes a new tax on digital advertising, the Finance Bill defines "digital advertising," sets the rate, specifies the due date, and lays out penalties. This is where the rubber meets the road. The budget tells you what the government wants. The Finance Bill tells you how it will make it happen.


    Money Bills vs. Other Finance Bills: The Constitutional Fine Print

    Not all Finance Bills are equal. The Constitution draws sharp lines between three categories: Money Bills (Article 110), Finance Bills under Article 117(1), and Finance Bills under Article 117(3). These distinctions decide which house of Parliament has real power—and which is sidelined.

    A Money Bill is the most restrictive. It can only be introduced in the Lok Sabha, and the Rajya Sabha can’t amend it. The Speaker certifies whether a bill qualifies as a Money Bill, a power that’s sparked fierce debate. The Supreme Court has upheld the Speaker’s certification but acknowledged that the Money Bill route could be misused to bypass the Rajya Sabha.

    Finance Bills under Article 117(1) are broader. They include provisions that would qualify as Money Bills under Article 110 and other general legislative matters. This gives the government flexibility to bundle tax changes with unrelated policy tweaks. The Rajya Sabha can propose amendments, but the Lok Sabha can reject them.

    Finance Bills under Article 117(3) deal exclusively with expenditures from the Consolidated Fund of India—how public money is spent, not how it’s raised. These are less common in annual budgets, which focus on revenue.

    There, the House of Lords has no power to amend Finance Bills. This has led to controversies when governments “tack on” non-financial measures to avoid upper-house scrutiny. Peers have complained, but the constitutional rule is clear: the Commons holds fiscal supremacy.


    Parliamentary Procedure: How Finance Bills Skip the Usual Hurdles

    Finance Bills don’t follow the same path as ordinary bills. Their procedure prioritizes speed and executive control—sometimes at the expense of scrutiny.

    In the UK, the Public Bill Committee for a Finance Bill is roughly double the size of those for regular bills, often up to 40 members.

    The Rajya Sabha’s role is constrained. For Money Bills, it has no power to amend or reject. For other Finance Bills, it can propose changes, but the Lok Sabha can override them with a simple majority.

    Once both houses approve the bill (or the Lok Sabha overrides the Rajya Sabha), it goes to the President for assent. After assent, the Finance Bill becomes the Finance Act, and its provisions take effect—often retrospectively.


    The Finance Act: From Paper to Law

    The moment the President signs the Finance Bill, it becomes the Finance Act. This isn’t just a name change. It’s when budget proposals become binding law. Taxpayers must comply, the tax department can enforce, and courts can interpret.


    Political and Constitutional Tensions: More Than Just Tax Law

    Finance Bills aren’t just technical documents. They’re flashpoints for constitutional battles, executive overreach, and bicameral friction.

    In the Rajya Sabha, the opposition can delay or amend non-Money Bills, but the Lok Sabha can override those changes.


    Global Comparisons: How Other Democracies Handle Finance Bills

    In the United Kingdom, the House of Commons holds exclusive authority over Finance Bills. This reflects the principle that taxation requires representation, as the Commons is elected. But the Lords has criticized governments for “tacking” non-financial measures onto Finance Bills.

    This contrasts sharply with India’s Money Bill provisions, where the Rajya Sabha’s role is severely limited.

    In Australia, the Senate has equal power with the House over money bills, except for those appropriating funds for ordinary annual government services.


    Criticisms and Controversies: The Dark Side of Finance Bills

    Finance Bills aren’t without critics. Three major controversies stand out: executive overreach, lack of transparency, and retrospective taxation.

    Executive Overreach

    Lack of Transparency

    Retrospective Taxation

    Judicial Deference


    The Future of Finance Bills: Digital Taxation, AI, and Climate Policy

    Digital Taxation The rise of the digital economy has forced governments to rethink tax frameworks.

    AI and Tax Compliance

    Climate Finance

    Legislative Reform


    Can Finance Bills Remain Both Powerful and Accountable?


  • **What Is Finance in Simple Words?: Breaking Down the Evidence**

    **What Is Finance in Simple Words?: Breaking Down the Evidence**

    Header image source: Corporate Finance: Definition and Activities via Investopedia via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Finance is the system that moves, measures, and multiplies money across personal, corporate, and public branches
    • Core finance tools include time value of money, risk assessment, and financial statements
    • Finance evolved from medieval debt settlement to today’s digital markets and quantitative models

    Finance isn’t about money sitting still. It’s about money in motion—invested, borrowed, lent, budgeted, saved, forecasted—with every action measured, valued, and designed to shape what comes next. The Corporate Finance Institute defines finance as a set of activities. That’s the key. Finance happens when a bank finances a loan or an investor allocates capital. Merriam-Webster’s definition—"money or other liquid resources"—misses the point entirely. Money is just the raw material. Finance is the system that moves it, measures it, multiplies it.

    That system splits into three branches—personal, corporate, public—each using the same tools but at different scales. The question is always the same: How do we use money today to achieve goals tomorrow?


    The Three Branches of Finance: Who Uses It and Why

    Personal Finance: Money Management for Individuals

    Personal finance is the branch everyone touches, whether they realise it or not. It’s about saving for emergencies, investing for retirement, borrowing for a home, budgeting to avoid debt. Investopedia frames it as managing money for long-term security (retirement, education funds) and short-term needs (paying bills, building an emergency fund). The tools are familiar—mortgages, credit cards, savings accounts, 401(k)s—but the principles are universal: time value of money, risk tolerance, opportunity cost.

    Take a student loan versus the stock market. The math is clear, but the decision hinges on trade-offs. Finance gives you the framework to quantify them. Should you take a 3% mortgage or a 5% personal loan? The numbers don’t lie, but the choice depends on your goals, timeline, and appetite for risk.

    Corporate Finance: How Businesses Fund Growth

    Corporate finance is where things get abstract but no less critical. It’s about how businesses raise capital, deploy it, and return value to shareholders. The Corporate Finance Institute frames it as maximising shareholder value while balancing risk, liquidity, and growth. This means issuing stocks, taking on debt (bonds, loans), managing cash flow, and making investment decisions—like building a new factory or acquiring a competitor.

    A key concept here is capital structure—the mix of debt and equity a company uses to fund operations. Too much debt, and the company risks bankruptcy. Too little, and it might miss growth opportunities. Then there’s working capital management, ensuring liquidity to cover day-to-day operations. Tesla burned through cash for years before turning a profit—corporate finance dictated how much debt it could take on and how long investors would tolerate losses.

    Public Finance: How Governments Spend (and Tax)

    Public finance is the least visible but most consequential branch for most people. It’s how governments collect revenue (taxes, tariffs) and allocate it (infrastructure, welfare, defence). Investopedia describes it as the study of government spending and debt issuance, including fiscal policy (taxation, spending) and monetary policy (interest rates, money supply). The goal? Stabilise the economy, fund public goods, redistribute wealth—or fail to, depending on political priorities.

    The U.S. federal budget in 2023 allocated $1.7 trillion to mandatory spending (Social Security, Medicare) and $1.4 trillion to discretionary spending (defence, education). Public finance determines how those numbers are calculated, justified, and adjusted. Should the government issue bonds to fund a new highway? Should it raise taxes to reduce the deficit? These aren’t just political questions—they’re financial calculations with real-world consequences.

    The Overlap: Same Tools, Different Scales

    All three branches rely on the same core activities:

    • Borrowing (mortgages, corporate bonds, government debt).
    • Investing (stocks, real estate, infrastructure projects).
    • Forecasting (retirement planning, earnings projections, GDP growth).

    The difference is scale and stakes. A miscalculation in personal finance might mean delaying retirement. In corporate finance, it could bankrupt a company. In public finance, it could trigger a recession.


    Finance as a Measurement System: Turning Intuition Into Numbers

    Finance doesn’t invent new truths—it quantifies what we already sense intuitively. OpenStax puts it well: finance "attempts to measure with numbers what we already ‘know’ about financial situations. " A business owner knows a project is profitable, but finance proves it with ROI calculations, payback periods, and net present value (NPV). A homebuyer feels a mortgage is affordable, but finance confirms it with debt-to-income ratios and amortisation schedules.

    The Tools of Measurement

    1. Time Value of Money (TVM): The foundation of finance. A dollar today is worth more than a dollar tomorrow because it can be invested to earn returns. TVM explains why banks charge interest—they’re compensating for the time value of their money—and why investors discount future cash flows.
    2. Risk Assessment: Finance quantifies uncertainty. Credit scores (FICO), volatility metrics (beta), and Value at Risk (VaR) models turn "gut feelings" about risk into actionable data. A bond rated BBB+ is less risky than one rated CCC, but finance tells you how much less risky—and what that means for your portfolio.
    3. Financial Statements: The scorecards of finance. A balance sheet shows what a company owns (assets) and owes (liabilities). An income statement tracks revenue and expenses. A cash flow statement reveals how money moves in and out. Together, they turn business decisions into trackable, comparable data.

    Why Measurement Matters

    Without measurement, finance would be guesswork. Numbers make it predictable, comparable, improvable. Consider two investments:

    • Investment A: 10% return, 15% volatility.
    • Investment B: 8% return, 5% volatility.

    Which is better? It depends on your risk tolerance—but finance gives you the language to discuss the trade-off. Without those numbers, you’re just guessing.


    The Core Activities of Finance: What It Actually Does

    Finance isn’t a monolith—it’s a collection of actions that move money through the economy. Here’s what those actions look like in practice:

    Investing: Allocating Capital for Future Returns

    Investing is about putting money into assets (stocks, bonds, real estate, startups) with the expectation of future returns. The driving principle is the risk-return tradeoff: higher potential rewards usually mean higher risk. Investopedia frames it as the balance between growth and safety—stocks offer growth but volatility; bonds offer safety but lower returns.

    Key concepts:

    • Diversification: Spreading investments across assets to reduce risk (e.g., holding stocks, bonds, and cash).
    • Asset allocation: Dividing a portfolio between different asset classes (e.g., 60% stocks, 30% bonds, 10% cash).
    • Liquidity: How easily an asset can be converted to cash (a savings account is liquid; a rental property is not).

    Warren Buffett’s investment strategy—buying undervalued companies and holding them long-term—is a financial decision rooted in measurement (price-to-earnings ratios, cash flow analysis) and patience.

    Borrowing and Lending: The Engine of Economic Growth

    Borrowing and lending move money from those who have it (savers, investors) to those who need it (borrowers, businesses, governments). The cost of this money is interest, which reflects:

    • Time value of money (compensation for waiting).
    • Risk (higher risk = higher interest rates).
    • Inflation (lenders demand returns that outpace rising prices).

    OpenStax highlights how this works in practice: a bank finances a mortgage by lending money to a homebuyer, who repays it with interest over 30 years. The bank’s profit comes from the spread—the difference between the interest it pays depositors and the interest it charges borrowers.

    Budgeting: Aligning Spending with Goals

    Budgeting is the planning of income and expenses to avoid deficits and achieve goals. It’s used by:

    • Individuals (tracking monthly spending, saving for a vacation).
    • Businesses (forecasting revenue, controlling costs).
    • Governments (balancing tax revenue with spending priorities).

    The Corporate Finance Institute calls budgeting the cornerstone of financial planning—without it, spending spirals out of control. A company that budgets poorly might run out of cash. A government that does so might face a debt crisis.

    Forecasting: Predicting the Future (With Caveats)

    Forecasting uses historical data, statistical models, and assumptions to predict future financial conditions. It’s critical for:

    • Businesses (projecting sales, cash flow).
    • Investors (predicting market trends).
    • Governments (estimating tax revenue, GDP growth).

    But forecasting is notoriously unreliable. The 2008 financial crisis exposed flaws in models that assumed housing prices would keep rising. Still, finance relies on forecasting because decisions must be made today—even if the future is uncertain.


    The Historical Roots: From Settling Debts to Global Markets

    Finance didn’t emerge fully formed. It evolved over centuries, shaped by trade, war, and innovation. The word itself comes from Old French finer (c. 1350), meaning "to settle a debt"—a nod to its origins in trust and obligation. Early finance was simple: barter, then coinage, then lending (often by merchants or temples). But the real revolution came with the rise of markets, credit, and institutions.

    Key Milestones

    1. Medieval Merchant Banks (12th–15th centuries): Italian bankers like the Medici family pioneered letters of credit, enabling long-distance trade without carrying gold.
    2. Joint-Stock Companies (17th century): The Dutch East India Company (1602) issued shares to investors, creating the first modern stock market in Amsterdam.
    3. Industrial Revolution (18th–19th centuries): Railroads, factories, and telegraphs required massive capital—leading to the rise of corporate finance (issuing stocks and bonds) and central banks (like the Bank of England).
    4. Modern Financial Theory (20th century): Academics like Harry Markowitz (portfolio theory) and Eugene Fama (efficient markets hypothesis) turned finance into a quantitative discipline.
    5. Digital Finance (21st century): The internet enabled online banking, algorithmic trading, and blockchain—democratising (and complicating) finance.

    The Big Picture

    Finance began as a tool for trust—settling debts, facilitating trade—and became a system for growth. Today, it’s the invisible infrastructure of the global economy, enabling everything from student loans to trillion-dollar mergers.


    Finance vs. Economics: What’s the Difference?

    Finance and economics are often conflated, but they’re distinct disciplines. Economics studies broad resource allocation—how societies produce, distribute, and consume goods and services. Finance zooms in on money—how it’s raised, invested, and managed by individuals, companies, or governments.

    Economics: The Big Picture

    Economics splits into two main branches:

    1. Macroeconomics: Studies aggregate phenomena like GDP, inflation, unemployment, and fiscal policy.
    1. Microeconomics: Studies individual actors—consumers, firms, industries—and how they make decisions.

    Finance: The Applied Side

    Finance is applied economics—it uses economic principles but focuses on financial instruments and decisions. Key areas:

    • Corporate finance: How businesses raise and deploy capital.
    • Investments: How individuals and institutions allocate assets.
    • Financial markets: How stocks, bonds, and derivatives are traded.

    The Divide in Practice

    Economics provides the theory. Finance provides the tools.


    Why Finance Matters: The Invisible Force Behind Daily Life

    Finance isn’t just for bankers or Wall Street. It’s embedded in everyday decisions, often invisibly. Here’s how it shapes lives:

    For Individuals

    • Borrowing: Mortgages enable homeownership. Student loans fund education. Without finance, these would be out of reach for most people.
    • Investing: Retirement accounts (401(k)s, IRAs) grow wealth over time—$10,000 invested at 7% annually becomes $76,000 in 30 years.
    • Budgeting: Tracking income and expenses prevents debt spirals.

    For Businesses

    • Capital Raising: Startups raise money via venture capital. Corporations issue stocks and bonds. Without finance, innovation would stall.
    • Risk Management: Insurance, hedging, and diversification protect against losses. Airlines hedge fuel costs. Farmers hedge crop prices.
    • Growth: Finance funds expansion—whether it’s a local bakery taking out a loan or Amazon issuing bonds to build warehouses.

    For Governments

    • Public Finance: Taxes fund schools, roads, and healthcare. The U.S. federal budget allocates **$1.
    • Monetary Policy: Central banks (like the Federal Reserve) set interest rates and regulate money supply to stabilise economies. The 2008 financial crisis led to quantitative easing (QE), where the Fed bought $4.5 trillion in bonds to lower interest rates.

    The Bottom Line

    Finance is the language of decision-making—whether you’re buying a house, launching a startup, or voting on fiscal policy. Ignore it, and you’re flying blind.


    The Dark Side: When Finance Goes Wrong

    Finance is a tool, and like any tool, it can be misused. History is littered with examples of finance amplifying crises, exacerbating inequality, and prioritising short-term gains over long-term stability.

    Excessive Risk-Taking: The 2008 Financial Crisis

    The 2008 crisis was a perfect storm of financial innovation gone wrong:

    • Subprime mortgages: Banks issued loans to borrowers with poor credit, betting on rising housing prices.
    • Derivatives: Financial instruments like credit default swaps (CDS) allowed investors to bet on mortgage defaults—$62 trillion in notional value by 2007.
    • Leverage: Investment banks like Lehman Brothers borrowed $30 for every $1 in equity, magnifying losses.

    When housing prices fell, the system collapsed. The result:

    • $13 trillion in global losses.
    • 9 million Americans lost their homes.
    • Dodd-Frank Act (2010): New regulations to prevent another crisis.

    Inequality: The Rich Get Richer

    Finance doesn’t just allocate resources—it concentrates wealth. Why?

    • Access: Wealthy individuals and institutions have better investment opportunities (private equity, hedge funds).
    • Tax advantages: Capital gains taxes are lower than income taxes in many countries.
    • Financialisation: The economy has shifted from production to speculation—more money is made trading assets than building things.

    Short-Termism: Sacrificing the Future for Today

    Companies often prioritise quarterly earnings over long-term sustainability. Examples:

    • Stock buybacks: Companies repurchase shares to boost earnings per share (EPS), often at the expense of R&D or employee wages. In 2022, U.S.

    Ethical Failures: Fraud, Predation, and Exploitation

    Finance has a long history of unethical behaviour:

    • Insider trading:

    The Key Insight

    Finance isn’t inherently good or bad—it’s a mirror of human behaviour. When used responsibly, it enables growth and opportunity. When abused, it amplifies greed and instability. The challenge is designing systems that incentivise the former.


    The Future of Finance: AI, Decentralisation, and Beyond

    Finance is not static. It’s evolving at breakneck speed, driven by technology, regulation, and shifting societal values. Here’s what’s next:

    AI and Automation: The Rise of the Machines

    Artificial intelligence is transforming finance from a human-driven industry to a data-driven one. Key developments:

    • Algorithmic trading: AI executes trades in milliseconds, dominating markets. In 2023, **70% of U.S.
    • Risk assessment: Machine learning improves credit scoring (e.g., ZestFinance) and fraud detection (e.g., Feedzai).

    4 trillion in assets**, offering low-cost, algorithm-driven portfolios.

    Decentralised Finance (DeFi): Cutting Out the Middleman

    DeFi uses blockchain technology to create financial systems without banks or governments. Key features:

    • Smart contracts: Self-executing agreements on blockchains like Ethereum. Example: Uniswap allows peer-to-peer trading without a central exchange.
    • Lending/borrowing: Platforms like Aave let users lend crypto and earn interest—no credit checks, no banks.
    • Stablecoins: Cryptocurrencies pegged to fiat currencies (e.g., USDC, Tether) enable borderless transactions.

    The big question: Can DeFi scale without sacrificing security or inclusivity?

    Sustainable Finance: Money with a Conscience

    Investors are increasingly demanding environmental, social, and governance (ESG) criteria. Key trends:

    • Green bonds: Debt issued to fund eco-friendly projects (e.g., renewable energy).
    • Impact investing: Investments aimed at measurable social or environmental impact (e.g., affordable housing, clean water).

    Critics argue ESG is vague and sometimes misleading—but the shift is undeniable. BlackRock, the world’s largest asset manager, now considers ESG factors in all its investments.

    Central Bank Digital Currencies (CBDCs): The Future of Money?

    Governments are experimenting with digital versions of fiat currencies:

    • The digital euro: The European Central Bank is exploring a blockchain-based euro.
    • The U.S. digital dollar: The Federal Reserve is researching a CBDC, though progress is slow.

    CBDCs could reduce cash usage, improve financial inclusion, and combat illicit finance—but they also raise privacy concerns (governments tracking transactions).

    The Big Question: Inclusive or Concentrated?

    The future of finance could go in two directions:

    1. More inclusive: Fintech and DeFi democratise access to financial services (e.g., M-Pesa in Kenya, Chime in the U.S.).
    2. More concentrated: Big tech (Apple, Google, Amazon) and Wall Street monopolise finance, leaving small players behind.

    Which path will dominate? The answer depends on regulation, innovation, and public demand.


    Finance is the science and practice of managing money—not as a static resource, but as a dynamic system of measurable actions that shape the future. It operates at three scales—personal, corporate, and public—but follows the same core logic: allocate resources today to achieve goals tomorrow. From its origins in settling debts to today’s AI-driven markets, finance has evolved into the invisible infrastructure of modern life, enabling growth, innovation, and risk—but also carrying the potential for instability and inequality. Whether you’re saving for retirement, launching a startup, or voting on fiscal policy, finance is the language of decision-making. The real question isn’t what is finance?—it’s what will you do with it? And will the systems we build prioritise fairness, or just efficiency?


  • **What Is Business Finance? A Data-Driven Breakdown of Its Core Purpose and Mechanics**

    **What Is Business Finance? A Data-Driven Breakdown of Its Core Purpose and Mechanics**

    Header image source: What are the Five Goals for Business Finance? | FutureBusiness via Future Business via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Business finance covers capital, allocation, and performance measurement
    • Debt vs equity financing involves trade-offs in control and risk
    • Financial statements and KPIs are essential for strategic decisions

    As one definition puts it: business finance is "the way a company gets money, spends it, and tracks whether those choices are working. " That last part—tracking—is what separates deliberate strategy from blind gambling. Without it, you’re not running a business. You’re hoping.

    This isn’t some abstract corner of corporate life. It’s one of three core branches of finance, alongside personal and public finance, and it operates by its own brutal logic. One perspective defines business finance as managers applying financial principles to maximise firm value in a risky environment. Not theoretical risk. Real risk—payroll that won’t clear, suppliers demanding payment, expansion that could sink the company.


    The Three Pillars Aren’t Theory. They’re Survival.

    Business finance stands on three functions, and every major decision flows through them. These aren’t academic boxes to tick. They’re the difference between growth and collapse.

    1. Raising capital Money doesn’t appear. It’s sourced—through debt, equity, or internal cash flow. Debt means loans or bonds, repaid with interest. Equity means selling shares, trading ownership for capital. Internal cash flow comes from revenue, but it’s unpredictable. One definition describes this as "the funds and credit that are used in a business to finance its operations. " Every dollar raised has a cost—interest, dividends, or loss of control. There’s no free money.

    2. Strategic allocation Capital raised has to be deployed. That’s where decisions get real—hiring, R&D, equipment, expansion. One framework describes this as "deciding how to use" the money, but that undersells it. This isn’t spending. It’s investing. A new machine might cut production costs by 15%, but only if the upfront cost doesn’t strangle cash flow. This can be described as the "analytical framework" of business finance. Without it, you’re guessing.

    3. Performance measurement Did the investments work? Are the funding choices sustainable? Financial statements—balance sheets, income statements, cash flow statements—are the scorecards. KPIs like ROI, working capital, and burn rate turn outcomes into numbers. One perspective bluntly states that business finance is about tracking "whether those choices are working. " If they’re not, the framework demands changes. No excuses.


    The Funding Landscape Isn’t Binary—It’s a Spectrum of Trade-Offs

    Business finance isn’t monolithic. The funding a company uses varies by duration, structure, and risk. Business finance can be grouped by "where funds come from, how they’re structured, and how long they last. " That taxonomy breaks into four main types, each with its own trade-offs.

    Short-term vs. long-term Short-term finance covers immediate needs—payroll, inventory, cash flow gaps. Think lines of credit, trade credit, invoice financing. Long-term finance funds growth—equipment, real estate, expansion. Bonds, term loans, equity. Both are listed in standard classifications, but the distinction is critical. Short-term finance is about survival. Long-term finance is about scaling. Mix them up, and you’re in trouble.

    Debt vs. equity Debt means borrowing—loans, bonds, credit lines—repaid with interest. Equity means selling ownership—venture capital, public stock offerings. Debt preserves control but adds repayment pressure. Equity avoids debt but dilutes ownership. Standard breakdowns highlight the trade-offs. Neither is inherently better. The right choice depends on the company’s stage, risk tolerance, and growth trajectory.

    Hybrids and alternatives Beyond debt and equity, newer models are emerging. Revenue-based financing ties repayments to revenue, not fixed schedules. Crowdfunding turns customers into investors. This evolution is reflected in how business finance "can be grouped by where funds come from. " The landscape is expanding, but the core question remains: what’s the cost, and what’s the control?


    Business Finance Isn’t Personal Finance on a Bigger Scale

    Business finance and personal finance share principles—budgeting, saving, investing—but their stakes and strategies diverge sharply. As one perspective puts it: "While personal and business finance share basic principles, they differ greatly when it comes to scope, clarity, and strategic finance. "

    Scope and complexity Personal finance deals with individuals—salaries, mortgages, retirement. Business finance deals with organisations—payroll, suppliers, taxes, expansion. The scale is different, but so is the complexity. Businesses operate in a web of regulations, market conditions, and competitive pressures. A misstep in personal finance might mean a delayed vacation. A misstep in business finance might mean insolvency.

    Calculated risks Personal finance is risk-averse. You save for emergencies, diversify investments, avoid debt. Business finance embraces risk—strategically. Business finance "accepts calculated risks aligned with growth potential, often leveraging debt strategically. " A company might take on debt to expand, knowing the ROI will outpace the interest. That’s not reckless—it’s deliberate. But it’s a mindset that doesn’t translate to personal finance.

    Common pitfalls The biggest mistake? Blurring the lines. Owners often "struggle when applying personal finance mindsets to business decisions, or vice versa. " Using a business credit card for personal expenses, or vice versa, muddies financial tracking. Worse, it distorts decision-making. Business finance demands discipline. Personal finance allows more flexibility.


    Finance Isn’t an Abstract Discipline—It’s the Backbone of Daily Operations

    Business finance isn’t some theoretical exercise. It dictates daily decisions. As one perspective makes clear: "Understanding business finance isn’t just for accountants—it shapes nearly every decision you make, from hiring to expanding to handling a slow quarter. "

    Hiring and expansion Growth requires capital. Can the company afford to hire? Should it lease or buy equipment? Financial planning answers these questions. Cash flow forecasts dictate whether expansion is feasible. Without them, growth becomes a gamble. Business finance "supports ongoing operations," but it also enables scaling. The difference between a stagnant company and a growing one often comes down to financial planning.

    Crisis management Downturns are inevitable. Strong finance enables survival. Reserves, credit access, contingency plans keep a business afloat during slow quarters. This can be framed as "handling a slow quarter," but it’s more than that. It’s about resilience. Companies with weak finance fold during crises. Those with strong finance pivot.

    Everyday choices Even small decisions—suppliers, inventory, pricing—hinge on financial constraints. Can the company afford to switch suppliers for a 5% cost saving? Does inventory turnover justify bulk purchases? These aren’t just operational questions. They’re financial ones. As one perspective puts it succinctly: business finance "shapes nearly every decision. "


    The Tools Aren’t Optional—They’re the Difference Between Clarity and Chaos

    Business finance doesn’t run on intuition. It runs on data, tools, and metrics. The core tools are financial statements, budgeting, and KPIs—each serving a specific purpose.

    Financial statements Three documents track a company’s health:

    • Balance sheet: Assets, liabilities, and equity at a point in time.
    • Income statement: Revenue, expenses, and profit over a period.
    • Cash flow statement: Inflows and outflows, separating operations, investing, and financing.

    These represent the "management of financial resources within an organisation. " They’re not just for accountants. They’re for decision-makers. A balance sheet reveals liquidity. An income statement shows profitability. A cash flow statement exposes vulnerabilities. Ignore them, and you’re flying blind.

    Budgeting and forecasting Budgets allocate resources. Forecasts predict outcomes. Together, they guide spending and investment. Business finance involves "planning" money. That planning isn’t static. It’s dynamic, adjusting to market conditions, growth, and crises. A budget without forecasting is just a wish list.

    Metrics KPIs quantify success. Key metrics include:

    • ROI: Return on investment. Is the money working?
    • Working capital: Current assets minus current liabilities. Can the company cover short-term obligations?
    • Burn rate: How fast is cash being spent? How long until it runs out?

    These represent the "performance measurement" pillar of business finance. Without them, companies can’t track progress—or failure. They’re the difference between informed decisions and guesswork.


    Poor Financial Management Isn’t a Mistake—It’s a Death Sentence

    Business finance isn’t optional. Weak finance leads to failure. As one perspective states bluntly: "The importance of business finance cannot be overstated, as it ensures the stability and scalability of a business. "

    Failure rates Cash flow mismanagement is a leading cause of business failure. Studies show that a significant percentage of small businesses fail due to poor cash flow management. That’s not a fluke. It’s a pattern. Without strong finance, companies run out of money—even if they’re profitable on paper. Profit isn’t cash. Cash is survival.

    Growth barriers Growth requires capital. Without it, businesses stagnate. Business finance "gives it room to grow. " But growth isn’t just about having money. It’s about deploying it strategically. A company might have cash but lack the financial planning to scale. That cash becomes a liability, not an asset.

    Competitive edge Strong finance enables agility. During crises, companies with reserves and credit access pivot. Those without fold. This can be framed as "informed decisions that protect your margins. " But it’s more than margins. It’s survival. The companies that thrive aren’t the ones with the best products. They’re the ones with the best financial management.


    The Future Isn’t Coming—It’s Already Here

    Business finance isn’t static. Technology, alternative funding, and global risks are reshaping the discipline. The question isn’t whether these changes will happen. It’s whether companies will adapt.

    Tech-driven finance AI and automation are streamlining financial management. Modern financial tools use AI to categorise expenses, detect anomalies, and optimise cash flow. The shift in business finance includes tools that shape decisions. The implication is clear: manual processes are giving way to data-driven insights. Companies that cling to spreadsheets will fall behind.

    Alternative funding Traditional debt and equity are no longer the only options. Crowdfunding, revenue-based financing, and peer-to-peer lending are disrupting the landscape. These are emerging types of business finance. The appeal? Flexibility. Companies can access capital without traditional lenders or investors. But flexibility comes with complexity. The rules are changing, and not everyone will keep up.

    Evolving risk landscape Climate change, geopolitics, and supply chain disruptions are reshaping financial strategies. Business finance operates in a "risky environment. " That risk isn’t just financial. It’s operational, regulatory, and existential. Companies are adapting—building resilience, diversifying supply chains, stress-testing financial models. The ones that don’t will pay the price.


    The Open Question Isn’t Whether Finance Matters—It’s Who Will Treat It as a Priority

    Business finance isn’t just about money. It’s about survival, growth, and strategy. The data is clear: companies with strong financial management thrive. Those without fail. The tools exist. The frameworks are proven. The consequences of neglect are dire.

    The question isn’t whether business finance matters. It’s whether leaders will treat it as the priority it is—or as an afterthought. The answer will determine who survives, who scales, and who gets left behind. The clock is ticking.


  • **What Is Finance Buddha? Inside India’s Top Digital Loan Aggregator and Its IPO Ambitions**

    **What Is Finance Buddha? Inside India’s Top Digital Loan Aggregator and Its IPO Ambitions**

    Header image source: On track to distribute Rs 2,000cr worth of loans, Finance Buddha might lend you the amount you need | YourStory via YourStory.com via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Finance Buddha covers 19,000 pincodes across India with proprietary loan-matching tech
    • IPO approval from NSE Emerge signals confidence in its advisory-driven aggregation model
    • Revenue depends entirely on lender commissions tied to loan disbursals

    Finance Buddha just got in-principle approval from NSE Emerge for an SME IPO. The Bengaluru-based digital loan aggregator covers 19,000 pincodes, works with banks and NBFCs, and calls itself “India’s top digital loan aggregator.” That’s not just bluster—its pincode reach is extensive, and its proprietary rules engine promises efficient matching.

    But what does that actually mean? And why does this IPO matter?


    How Finance Buddha Actually Works

    Finance Buddha doesn’t lend money. It connects borrowers with lenders—banks and NBFCs—and takes a commission when loans get disbursed. That’s the simple part. The complicated part is how it does that.

    When a borrower applies for a personal loan or home loan on Finance Buddha’s platform, the company’s rules engine evaluates the application against multiple lender criteria—credit score, income, employment type, loan amount—and matches it with the best offers. Borrowers see transparent comparisons, pick an offer, and Finance Buddha gets paid.

    This isn’t just a comparison tool. The company describes itself as having an “advisory-driven approach,” which suggests something more than just listing APRs. That’s a real differentiator in a market where aggregators often treat loans like commodities.

    Finance Buddha’s product lineup includes:

    • Unsecured loans: Personal and business loans, up to ₹50 lakh.
    • Mortgage loans: Home loans and loan against property (LAP).
    • Insurance: Distributed on behalf of insurers, though details are scarce.

    Revenue comes entirely from commissions or fees paid by lending partners. Payments are based on disbursals. That means Finance Buddha’s financial health is directly tied to loan volumes and the credit appetite of its partner banks and NBFCs.


    Who Built This?

    Finance Buddha was founded in 2012 by Vivek Bhatia, Parth Pande, and Parag Agarwal. The brief doesn’t say much about their backgrounds, but Chennai Angels invested in the company, citing the founders’ “domain competence and execution skills.” That’s a telling quote—it suggests they knew what they were doing in lending or fintech before starting Finance Buddha.

    The company covers 19,000+ pincodes. For context, major lenders serve thousands of cities across India. Finance Buddha isn’t a lender, so the comparison isn’t perfect, but the scale is still impressive for a company that operates through partnerships rather than its own balance sheet.


    The Tech Behind the Aggregation

    Finance Buddha’s rules engine is its competitive edge. The brief doesn’t spell out the mechanics, but here’s how it likely works:

    1. Data Intake: Borrowers submit applications with personal, financial, and loan-specific details.
    2. Pre-Qualification: The engine screens applicants against lender eligibility criteria—minimum credit score, income thresholds, etc.
    3. Matching: The engine ranks lenders based on the borrower’s profile, loan requirements, and lender risk appetite.
    4. Advisory Layer: Borrowers get curated offers with transparent terms, repayment schedules, and fees—possibly with contextual guidance like, “This lender is best for self-employed borrowers.”

    This isn’t just a database lookup. The "advisory-driven approach" implies dynamic decision-making to improve matches over time. For example, the engine would prioritise lenders based on their approval patterns for different applicant profiles.

    The brief also mentions “quick approvals and fast disbursal.” That’s table stakes in digital lending, but Finance Buddha’s tech could be optimising for speed by:

    • Pre-integrating with lender APIs to cut manual data entry.
    • Using alternative data—bank transaction history, utility payments—for applicants with thin credit files.
    • Automating document verification—Aadhaar, PAN, salary slips—via OCR or third-party services.

    Why India Needs Loan Aggregators

    India’s retail lending market is a mess. The country has numerous scheduled commercial banks and NBFCs, with growing demand for credit driven by digital adoption and financial inclusion.

    For borrowers, this fragmentation is a nightmare. Comparing loan offers across banks is time-consuming, and many lenders have opaque eligibility criteria. Aggregators like Finance Buddha solve this by centralising discovery and simplifying the application process.

    1. Digital Adoption: India has a large number of internet users, with fintech adoption growing. UPI transactions have seen significant growth.
    2. 2. Regulatory Support: Regulatory guidelines mandate transparency in loan disbursals and fee structures, which benefits aggregators that can show clear comparisons.
    3. Underserved Segments: Self-employed borrowers, gig workers, and small businesses often struggle to access formal credit. Aggregators can match them with niche lenders.

    Finance Buddha’s pincode coverage (19,000+) suggests it’s targeting both urban and semi-urban markets. That’s smart—Tier 2/3 cities are underserved by traditional lenders but have growing internet penetration and credit demand.


    What the IPO Approval Really Means

    Finance Buddha’s in-principle approval from NSE Emerge for an SME IPO is a big deal. Here’s why:

    1. Growth Ambitions: The company is positioning itself as a scalable, tech-driven financial services platform, not just another loan marketplace. An IPO would provide capital for expansion.
    2. Market Validation: NSE Emerge’s approval suggests confidence in Finance Buddha’s business model and financials. SME IPOs aren’t just about growth—they’re scrutinised for sustainability.
    3. Competitive Positioning: A successful IPO could elevate Finance Buddha’s profile, attracting more lender partnerships and borrowers.

    The stated use of funds includes:

    • Expanding reach—deeper pincode penetration or new product lines.
    • Enhancing technology—upgrading the rules engine, improving fraud detection.
    • Deepening market penetration in retail lending.

    This isn’t just about raising capital. It’s about signalling maturity. Competitors have been exploring IPOs but haven’t pulled the trigger. Finance Buddha’s move could force other aggregators to accelerate their own fundraising plans.


    How Finance Buddha Stacks Up Against Competitors

    Finance Buddha isn’t alone in this space, but its differentiators are worth examining:

    | Competitor | Model | Key Differentiators | Finance Buddha’s Edge | |———————-|————————————|————————————————–|———————————————–| | BankBazaar | Loan and credit card aggregator | Strong brand, partnerships with major banks | Proprietary rules engine, advisory approach | | Paisabazaar | Loan and insurance aggregator | Backed by Policybazaar, large marketing budget | Pan-India pincode coverage (19,000+) | | KreditBee | Direct digital lender | Focus on salaried and self-employed borrowers | Works with multiple lenders, not just its own | | MoneyTap | Hybrid aggregator/direct lender | Offers revolving credit lines | Wider product range (home loans, LAP) |

    Finance Buddha’s claim to being “India’s top digital loan aggregator” isn’t baseless. Its pincode coverage and proprietary tech give it scale advantages over smaller players. But competitors have stronger brand recognition and deeper pockets for marketing.

    The real threat might come from new entrants. New entrants with strong distribution ecosystems could disrupt the aggregator space. Finance Buddha’s IPO could be a preemptive strike to secure capital before such competitors ramp up.


    Risks and Challenges

    Finance Buddha’s model isn’t without risks:

    1. Dependence on Lending Partners: Its revenue is tied to loan disbursals. If partner banks or NBFCs tighten credit, volumes could plummet. The brief doesn’t mention diversification into non-loan products like insurance or investments, which could mitigate this risk.
    2. Tech Risks: The rules engine must stay ahead of fraudsters and comply with evolving RBI guidelines. Any failure here could erode lender trust.
    3. Competition: Competitors have stronger brand recall, while direct lenders can offer faster disbursals by underwriting in-house.
    4. IPO Execution: SME IPOs face higher volatility and lower liquidity. A botched listing could damage investor confidence.

    There’s also the question of unit economics. The brief doesn’t disclose margins or customer acquisition costs. Aggregators typically operate on thin margins, so scale is critical. Finance Buddha’s pincode coverage suggests it’s achieved scale, but the IPO prospectus will need to prove profitability.


    Where Does Finance Buddha Go From Here?

    Finance Buddha’s post-IPO plans are clear: expand reach, enhance tech, and deepen market penetration. But the long-term vision could be more ambitious. Here’s what might come next:

    1. New Product Lines: The company could add BNPL or credit cards to its portfolio, leveraging its lender partnerships.
    2. Full-Stack Fintech: It could evolve into a one-stop shop for lending, insurance, and investments—similar to Policybazaar’s model but with a stronger tech backbone.
    3. International Expansion: India’s digital lending boom is a template for other emerging markets—Indonesia, Nigeria. Finance Buddha’s tech could be exportable.

    The most interesting question is whether Finance Buddha can transition from a loan aggregator to a financial services platform without alienating its lender partners. Aggregators thrive on neutrality—if Finance Buddha starts underwriting loans itself or favouring certain lenders, it risks losing trust. The advisory-driven approach could be the key here, positioning the company as a trusted intermediary rather than a competitor.


    Is Finance Buddha a Big Deal?

    Finance Buddha is a well-executed niche player in India’s fintech ecosystem. It’s not revolutionary—loan aggregation has been around for years—but its proprietary tech, pincode coverage, and IPO ambitions make it a company to watch.

    The IPO isn’t just about raising capital. It’s a bet that India’s retail lending market is big enough for multiple aggregators to thrive, and that Finance Buddha’s tech-driven model can outpace competitors. If successful, it could set a precedent for other digital loan aggregators, proving that scale and specialisation—not just brand recognition—can win in fintech.

    The open question is whether Finance Buddha can maintain its neutrality while expanding. Aggregators succeed by being Switzerland—neutral, transparent, and borrower-friendly. If the IPO changes that, the company risks becoming just another sales channel for banks. But if it can balance growth with trust, Finance Buddha could redefine what it means to be a loan aggregator in the digital age.


  • **What Is Finance in Accounting? The Evidence-Backed Distinction**

    **What Is Finance in Accounting? The Evidence-Backed Distinction**

    Header image source: Finance vs. Accounting: What’s the Difference? | HBS Online via Harvard Business School Online via Google — cropped to 16:9 and colour-adjusted.

    Key takeaways

    • Accounting is retrospective and rules-based; finance is prospective and analytical.
    • Accounting provides the data; finance creates the strategy.
    • AI automates tasks but deepens the need for both disciplines.

    Finance in accounting isn’t redundant. It’s deliberate. Two disciplines, one framework—past precision meeting future strategy. Accounting records what happened. Finance decides what to do next. That’s the divide. And it’s why both matter.

    Casual conversation blurs them. Evidence doesn’t. Accounting is retrospective, rules-bound, exact. Finance is forward-looking, analytical, strategic. One fuels the other. Without accounting, finance starves for data. Without finance, accounting is just numbers in a ledger.


    Retrospective vs. Prospective: The Time Divide

    Accounting lives in the past. Completed transactions. Revenue earned. Expenses incurred. Assets acquired. The outputs? Financial statements—balance sheets, income statements, cash flow statements. Historical artifacts. A quarterly earnings report tells investors what happened last quarter. It doesn’t predict next quarter.

    Finance lives in the future. It starts where accounting ends. Take that $10 million revenue figure. A finance professional asks: What does this mean for next year? Reinvest? Issue debt? Return capital? Tools like discounted cash flow models, CAPM, scenario analysis—all built to project outcomes. The past is just the foundation.

    Accounting. As the evidence shows: Finance is more analytical and future-oriented, while accounting is more rules-based and retrospective. Not preference. Structure. Accounting documents. Finance strategizes.


    Rules vs. Judgment: Precision Meets Subjectivity

    Accounting follows rules. GAAP in the U.S. IFRS globally. Frameworks dictate how transactions are recorded, assets valued, statements presented. Auditors verify compliance. The goal? Consistency. Comparability.

    Finance has no rulebook. Only judgment. A 10% discount rate in a DCF model? Valid. 8%? Also valid. Depends on risk, market conditions, cost of capital. Growth rates, terminal values, capital structure—no “correct” answer. Only better or worse ones.

    The distinction is clear: There is more subjective judgment in finance and more precision in accounting. Not a flaw. A feature. Finance thrives on uncertainty. Accounting thrives on certainty. One can’t function without the other. A finance model is only as good as its accounting data. And accounting data is only useful if finance can act on it.


    The Asset Management Spectrum: Valuation vs. Optimization

    Accounting records assets at historical cost or fair value. Compliance with depreciation, amortization, impairment tests. A factory on the balance sheet at $50 million net book value—original cost minus depreciation. Job done.

    Finance asks: Is this factory worth keeping? The $50 million is just a starting point. Project future cash flows. Discount them back. Compare to book value. Consider alternatives—sell, relocate, automate. The goal isn’t valuation. It’s optimization.

    HBS Online frames it as different levels of the asset management spectrum. Accounting scores. Finance plays.


    Data as Input vs. Data as Output

    Accounting’s outputs are financial statements. Standardized. Audited. Distributed. The official record.

    Finance’s inputs are those same statements. But not as final deliverables. As raw material. A DCF model starts with revenue and expenses, adjusts for non-cash items, projects cash flows. An LBO model uses debt and equity figures to structure a deal. Stress tests assess liquidity under adverse scenarios.

    The evidence shows: Accounting focuses on properly recording what has happened, while finance deals with assets, liabilities, and equity more broadly. Sequential workflow. Accountant closes the books on December 31. Finance analyst uses them to pitch a January acquisition. Without accounting, finance builds on sand. Without finance, accounting is a ledger with no purpose.


    Career Paths and Education: Skills, Certifications, Outcomes

    Finance and accounting rank among the most popular business degrees—FAME framework (Finance, Accounting, Management, Economics). But the paths diverge.

    Accounting professionals master tax codes, audit procedures, ERP systems like SAP or Oracle. Certifications: CPA, CMA. Detail-oriented. Compliance-driven. Repetitive—reconciling accounts, preparing tax filings, ensuring GAAP adherence.

    Finance professionals focus on modeling, valuation, capital markets. Certifications: CFA, FP&A. Tools: Excel, Bloomberg, statistical software. Build DCF models. Analyze M&A deals. Manage portfolios. Analytical. Strategic. High-stakes.

    Both degrees are highly sought-after. Career paths reflect the disciplines. Accountants climb to controller or CFO through technical expertise. Finance professionals through strategic decision-making. One ensures the numbers are right. The other ensures they’re used right.


    Public and Private Sector Relevance

    Private sector: accounting ensures compliance. Public companies file quarterly and annual reports with the SEC. Private companies prepare statements for lenders, investors, buyers. The language of regulation and stakeholders.

    Finance drives growth. Raises equity. Issues debt. Pursues IPOs. Evaluates mergers. Divests underperforming units. Hedges currency risk. Without finance, companies stagnate.

    Public sector mirrors this. Governments track tax revenues, monitor expenditures, ensure budget adherence. Comptroller’s office records every dollar. But finance deploys them. Issue municipal bonds for a subway line? Shift a pension fund’s asset allocation? Finance questions. Informed by accounting.

    Both finance and accounting are highly valuable for assessing a company’s position and performance. Same for governments, nonprofits, households. Accounting tells you where you’ve been. Finance tells you where to go.


    The Convergence Point: Where Data Meets Decision

    Finance and accounting aren’t siloed. They converge. Historical data meets strategic decision-making.

    Financial reporting (accounting) informs valuation models (finance). Cost accounting (accounting) feeds capital budgeting (finance). Tax accounting (accounting) shapes financial planning (finance). The handoff is seamless.

    The evidence shows: Finance is more general and future-focused, while accounting works with existing records. Finance relies on accounting’s outputs. But accounting’s outputs are only useful if finance can act on them.

    Private equity firm evaluating an acquisition? Accountants ensure the target’s statements are accurate. Finance team builds a DCF model, assesses synergies, structures the deal. Neither completes the task alone. Together, they enable the transaction.


    The Future of the Divide: AI’s Role

    AI is reshaping both disciplines. Differently.

    In accounting, AI automates transaction recording, reconciliations, basic audits. RPA handles repetitive tasks. Frees accountants for complex standards—revenue recognition, lease accounting. But the core work—compliance, interpretation, sign-offs—remains human. AI can’t replace judgment in gray areas.

    In finance, AI enhances predictive modeling. Machine learning forecasts credit risk, optimizes portfolios, detects fraud. But these models rely on accounting’s clean, structured data. Garbage in, garbage out.

    The disciplines stay distinct. Integration deepens. AI bridges, doesn’t disrupt. Accountants spend less time on data entry, more on interpretation. Finance professionals spend less time on manual modeling, more on strategy.

    The open question isn’t whether finance and accounting will merge. It’s whether the next generation will master both—or if specialization remains the norm. The answer shapes the future of financial management.